What is business finance? Business finance is the process of planning, obtaining, managing, and using money to start, operate, and grow a business. It includes everything from paying employees and managing daily cash flow to securing loans, evaluating investments, and deciding whether expansion is financially worthwhile.
Imagine owning a small coffee shop.
It’s a beautiful little place. Your customers love the coffee, your employees are friendly, and people regularly recommend you to their friends.
Business is growing.
Wonderful news, right?
But there’s a problem.
Your supplier needs payment this Friday. Your employees get paid on Monday. Your rent is due next week, and a corporate customer won’t settle its large catering invoice for another 30 days.
Your shop is making sales, but your bank balance is getting uncomfortable.
Welcome to one of the most important lessons in running a business: a company can be profitable on paper and still struggle to pay its bills.
That’s why business finance matters.
It isn’t just about borrowing money from banks or convincing investors to fund your next big idea.
It’s about understanding where money comes from, where it goes, when it arrives, and whether the decisions you’re making actually strengthen your business.
At Weird Wealth, we’re always exploring interesting ways to earn money. But running a financially healthy business requires something beyond a clever product or a growing customer base.
Let’s explore the financial side of entrepreneurship in plain English.
Key Takeaways
- Business finance covers funding, budgeting, cash flow, investment decisions, financial planning, and risk management.
- Businesses typically obtain capital through their own earnings, owner contributions, debt financing, equity financing, or other funding arrangements.
- Profit and cash flow are different; a business can report a profit while experiencing a cash shortage.
- The three fundamental financial statements are the income statement, balance sheet, and cash flow statement.
- Working capital helps measure a company’s short-term financial position.
- Borrowing can support growth, but financing costs and repayment obligations can also weaken a business.
- Financially responsible growth requires evaluating profitability, cash requirements, and downside risks—not revenue alone.
What Is Business Finance in Simple Terms?
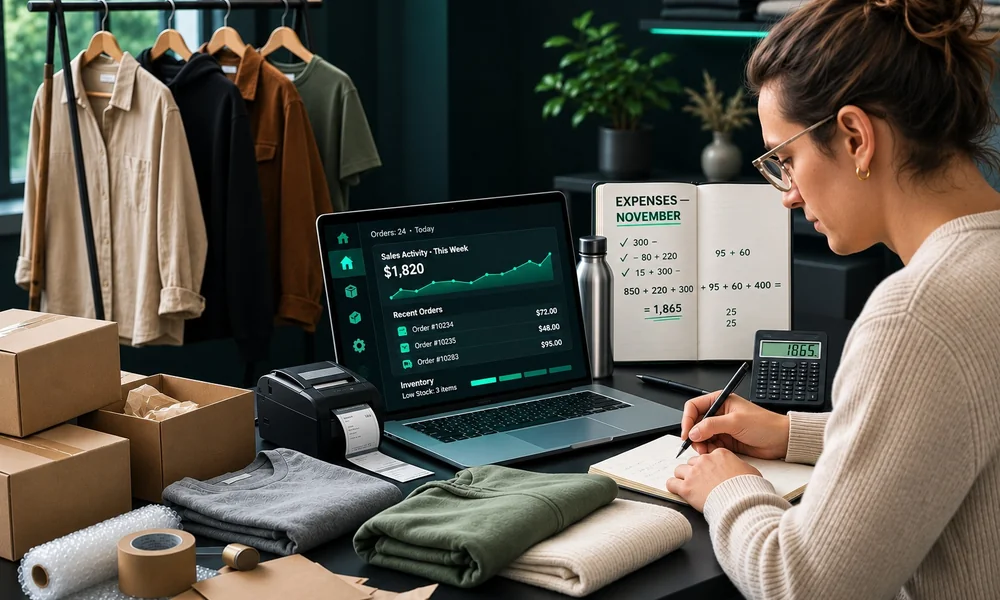
Business finance means managing the financial resources a business needs to function.
Suppose you want to open a small online clothing store.
Before selling your first product, you need to answer several questions.
How much will inventory cost?
What will you pay for your website?
How much cash do you need for shipping, refunds, and marketing?
What happens if customers take longer to buy than expected?
And where will you get the money to cover those costs?
Those are business finance questions.
Once the store begins operating, the questions change.
Are sales producing enough gross profit?
Can you afford to hire someone?
Should you borrow money to purchase more inventory?
Are your customers paying quickly enough?
Business finance helps answer these questions through financial records, forecasts, calculations, and judgment.
It connects everyday money management with long-term business decisions.
Why Is Business Finance Important?
You can have a brilliant product and still build a financially unstable company.
Imagine selling a product for $100.
Customers love it, and you’ve sold 1,000 units.
Your revenue is $100,000.
That sounds impressive.
But suppose producing, delivering, marketing, and operating the business costs $108,000.
You’ve made $100,000 in sales while recording an $8,000 loss under that simplified example.
Revenue alone doesn’t reveal business success.
Business finance helps owners understand whether their activities are sustainable.
It also supports decisions about hiring, pricing, equipment, borrowing, expansion, and preparing for unexpected expenses.
The goal isn’t to avoid every financial risk.
It’s to understand the risks before committing money.
The Three Main Types of Business Finance
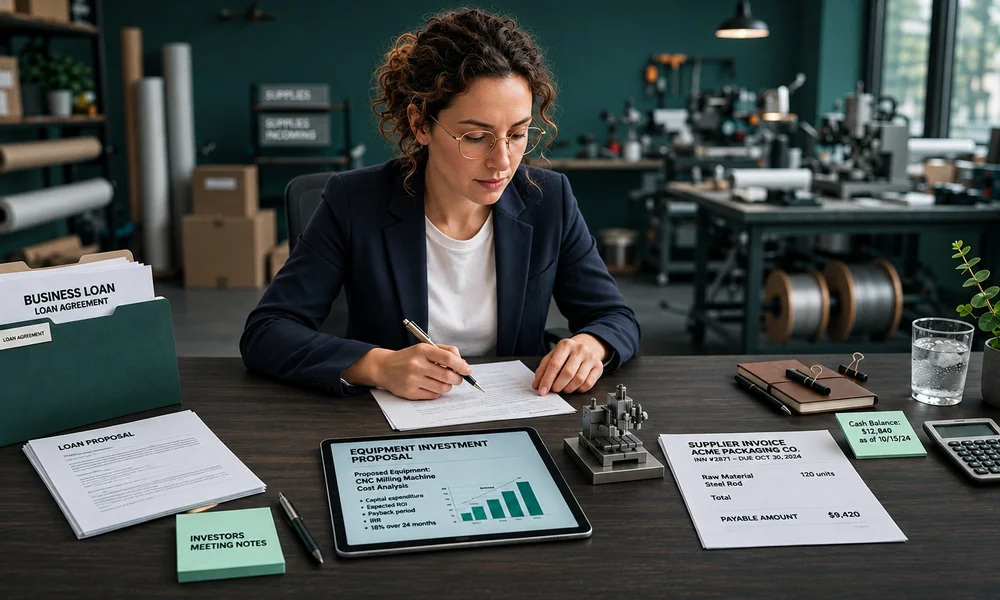
Business finance is often divided into three broad decision areas.
1. Financing Decisions
Where will the business obtain money?
Possible sources include owner savings, business earnings, loans, investors, and other funding arrangements.
Each source involves different costs and obligations.
2. Investment Decisions
How should the business use its available money?
Perhaps it could purchase equipment, launch a product, expand into another location, or develop new software.
The question is whether the expected benefits justify the cost and risk.
3. Working Capital Decisions
How will the business meet its everyday financial obligations?
This involves cash, accounts receivable, inventory, and short-term liabilities.
A company that ignores working capital can struggle even when its long-term business model appears attractive.
These decisions are interconnected.
Borrowing to purchase inventory affects debt, cash flow, and operating risk simultaneously.
What Are the Sources of Business Finance?
There isn’t one best funding method for every company.
A neighborhood bakery and a venture-backed technology startup may need completely different financing arrangements.
Here are the common options.
1. Bootstrapping
Bootstrapping means funding the business primarily through the owner’s resources and the money the company generates.
For example, someone might launch a small design service using equipment they already own.
As customers pay, the owner reinvests part of the earnings.
The advantage is maintaining control without automatically taking on investor obligations.
The limitation is that growth may depend on available cash.
Using personal savings also introduces financial risk to the owner.
2. Business Loans
A business loan provides money that must generally be repaid according to a contract.
Loans may help fund equipment, inventory, expansion, or other eligible business expenses.
But borrowing involves interest, fees, repayment requirements, and sometimes collateral or personal guarantees.
A loan isn’t revenue.
It’s financing that creates an obligation.
3. Business Lines of Credit
A line of credit provides access to borrowing up to an approved limit, subject to the agreement.
This may help with temporary cash flow needs.
For example, a seasonal business might need additional working capital before its busiest sales period.
However, interest, fees, limits, and renewal conditions can make the facility costly or unavailable when conditions change.
4. Equity Financing
Equity financing involves raising capital by selling an ownership interest in the company.
An investor contributes money in exchange for an agreed stake or other equity-related rights.
Unlike an ordinary loan, equity investment generally doesn’t require scheduled principal and interest payments.
But it can dilute existing owners and affect control and future profit distributions.
5. Trade Credit
Suppliers sometimes allow businesses to receive goods or services before payment is due.
For example, a supplier might offer 30-day payment terms.
That can help manage timing differences between purchasing inventory and collecting sales.
However, late payments can damage relationships or lead to fees and tighter terms.
6. Revenue-Based Financing and Merchant Cash Advances
Some financing products provide upfront funding in exchange for payments connected to future revenue or receivables.
These arrangements can be more complicated than conventional loans.
The Consumer Financial Protection Bureau describes typical merchant cash advances as arrangements in which businesses receive an advance and repay a larger agreed amount. Repayment may come through a share of future sales or fixed daily withdrawals.
Before considering this type of funding, business owners should understand bank practices and financial terms and how deposit timing can affect available cash. Learning about banks that offer early direct deposit can also provide useful context when managing cash flow.
The effective financing cost can be substantial.
Review the total repayment obligation, collection frequency, fees, and what happens when sales decline.
Debt Financing vs. Equity Financing
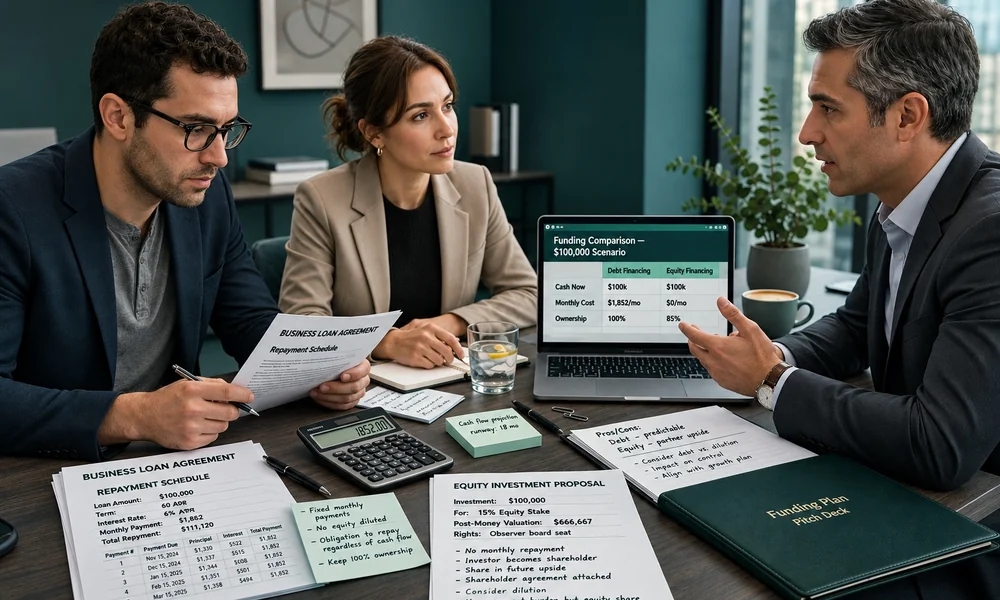
This is one of the most important comparisons for entrepreneurs.
| Feature | Debt financing | Equity financing |
| How capital is obtained | Borrowing | Selling an ownership interest |
| Repayment | Generally required | No ordinary loan repayment obligation |
| Interest | Usually applies | Generally no loan interest |
| Ownership dilution | Usually none | Usually yes |
| Financial risk | Debt payments and possible default | Reduced ownership and potential control changes |
| Investor or lender involvement | Depends on loan terms | Depends on shareholder agreements |
| Common use | Equipment, working capital, expansion | Startup funding and growth capital |
Imagine two founders seeking $100,000.
One accepts a loan and keeps their ownership, but the business must repay the debt.
The other sells an ownership stake and avoids ordinary loan repayments, but gives up a share of the company.
Neither arrangement is universally superior.
The right choice depends on the company’s financial position, expected returns, risks, and long-term goals.
What Are the Three Financial Statements?
Every serious business owner should understand three financial reports.
You don’t need to become an accountant.
But you should know what these documents tell you.
1. Income Statement
The income statement shows revenues and expenses over a period.
It helps determine whether the business generated a profit or loss.
For example:
| Income statement item | Monthly amount |
| Revenue | $30,000 |
| Cost of goods sold | $12,000 |
| Gross profit | $18,000 |
| Operating expenses | $11,000 |
| Operating profit | $7,000 |
This is a simplified example excluding financing costs, taxes, and other potential accounting items.
It demonstrates how a business can produce $30,000 in revenue while retaining much less as operating profit.
2. Balance Sheet
A balance sheet provides a snapshot of assets, liabilities, and equity at a particular date.
Its fundamental accounting equation is:
Assets = Liabilities + Equity
Suppose a business owns assets worth $100,000 and has liabilities of $35,000.
Its accounting equity would be $65,000.
That doesn’t necessarily mean the business could be sold for $65,000.
The balance sheet uses accounting measurements, and actual market value may differ.
3. Cash Flow Statement
A cash flow statement explains cash moving into and out of a business during a period.
It commonly separates cash flows into operating, investing, and financing activities.
This helps explain why profit and available cash don’t always move together.
The Most Important Lesson: Profit Is Not Cash
Let’s return to our coffee shop.
Imagine the owner signs a catering contract worth $10,000.
The customer receives the service in November but won’t pay until December.
Under accrual accounting, the business may recognize the revenue when earned, subject to the applicable accounting rules.
But the cash hasn’t arrived yet.
Meanwhile, the owner has already paid employees and suppliers.
This creates a timing problem.
A Simple Example
Suppose a design agency has the following monthly activity:
| Item | Amount |
| Revenue earned | $20,000 |
| Expenses recognized | $13,000 |
| Accounting profit | $7,000 |
| Cash collected from customers | $9,000 |
| Cash paid for operating expenses | $12,000 |
| Net operating cash movement, simplified | −$3,000 |
The company reports a $7,000 accounting profit under these assumptions.
Yet cash decreased by $3,000 from the simplified operating receipts and payments.
That’s possible because revenue recognition and cash collection can occur at different times.
A growing business can therefore face liquidity problems despite reporting profits.
What Is Working Capital in Business Finance?
Working capital measures a business’s short-term financial position.
The basic formula is:
Working Capital = Current Assets − Current Liabilities
Current assets can include cash, receivables, and inventory expected to be realized or used within the normal operating cycle.
Current liabilities include obligations such as short-term payables and other amounts due within the applicable period.
Imagine a business has:
Current assets of $80,000.
Current liabilities of $55,000.
Its working capital equals $25,000.
Positive working capital can provide a cushion for short-term obligations.
But it doesn’t automatically mean the business has $25,000 in its bank account.
Some assets may be tied up in inventory or unpaid customer invoices.
That’s why working capital should be examined alongside actual cash availability.
The Weird Wealth Cash Timing Gap
Here’s an original way to understand the financial challenges of small businesses.
We call it the Cash Timing Gap.
Instead of looking only at profit, examine how long your money remains committed before it returns as collected revenue.
Imagine an ecommerce company.
It pays a supplier on November 1.
The inventory arrives on November 10.
Customers purchase the products on November 20.
The company receives the money in its bank account on November 23.
The business paid cash 22 days before collecting customer proceeds.
That gap must be funded somehow.
It could be supported through existing cash, appropriate supplier terms, or suitable financing.
Now imagine the supplier offers payment terms allowing the company to pay on November 15 instead.
The gap between supplier payment and collection becomes eight days.
That improves cash timing without requiring the company to sell more products.
The interesting insight: sometimes improving payment terms creates more financial breathing room than increasing sales.
Of course, supplier negotiations, discounts, fees, and contractual obligations should be considered.
How Do Businesses Decide Whether an Investment Is Worthwhile?
Imagine you own a small printing business.
A new machine costs $20,000.
The supplier claims it could help you process orders faster.
Should you buy it?
The wrong approach is simply saying, “More capacity means more revenue.”
You need to estimate how much additional cash benefit the machine could produce.
Suppose the equipment is expected to generate $6,000 annually in incremental net cash benefit for five years, with no residual value and no additional upfront costs.
That would total $30,000 in undiscounted benefits.
Subtract the $20,000 initial cost, and the simple undiscounted surplus is $10,000.
But this calculation ignores the time value of money and uncertainty.
A more complete investment analysis may involve net present value, expected maintenance, financing costs, taxes, and alternative uses for the funds.
Why Net Present Value Matters
Net present value, or NPV, compares the present value of expected future cash flows with the initial investment.
The principle is that money received in the future isn’t necessarily worth as much as money available today.
NPV analysis also depends on the discount rate and the accuracy of forecasts.
An attractive projection can still produce a disappointing outcome if sales fall short or expenses exceed expectations.
The Four Business Finance Decisions Every Founder Faces
Here’s another practical way to organize business financial choices.
Decision One: How Much Money Do We Need?
Estimate startup costs, expected operating expenses, and suitable cash reserves.
Don’t assume that launching the business is the same as having enough money to sustain it.
Decision Two: Where Should the Money Come From?
Compare available funding methods.
Understand debt obligations, ownership dilution, guarantees, and other risks.
Decision Three: Where Should We Spend It?
Evaluate the expected benefits of equipment, inventory, hiring, technology, or marketing.
Prioritize decisions supported by evidence rather than excitement.
Decision Four: How Will We Know It’s Working?
Monitor cash flow, profitability, customer payments, costs, and progress toward financial goals.
This creates a cycle of planning, financing, investing, and measuring.
A business that raises money without measuring results may simply postpone its underlying problems.
What Is the Difference Between Business Finance and Accounting?
These two subjects are closely connected.
But they aren’t identical.
Accounting focuses on recording, organizing, and reporting financial information.
Business finance uses financial information to plan and make decisions about funding, investment, operations, and risk.
For example, accounting tells you that your company spent $12,000 on equipment.
Finance helps you evaluate whether buying that equipment was a sensible decision.
Accounting tells you that customers owe your business $40,000.
Finance asks whether you can meet upcoming payroll obligations before those invoices are collected.
Without reliable accounting, financial decisions are built on uncertain information. A clear understanding of financial accounting basics helps businesses maintain accurate records and understand their financial position.
Without financial analysis, accurate records may never influence how the business operates. Regular financial analysis for better business decisions helps turn those records into practical insights that guide planning and growth.
Business Finance vs. Personal Finance
Personal finance concerns the financial decisions of individuals and households.
Business finance focuses on the financial resources and obligations of businesses.
| Area | Personal finance | Business finance |
| Income | Salary, earnings, investment income | Sales and operating revenue |
| Expenses | Housing, food, household bills | Payroll, suppliers, rent, operations |
| Borrowing | Personal loans and mortgages | Business loans and credit facilities |
| Savings | Emergency funds and personal goals | Operating reserves and liquidity |
| Investment | Retirement and personal assets | Equipment, expansion, business projects |
| Reporting | Budgets and personal statements | Income statement, balance sheet, cash flow statement |
For entrepreneurs, it’s particularly important to distinguish business money from personal spending.
Separating records and accounts where appropriate can improve bookkeeping, tax administration, and financial visibility.
Your business’s bank balance is not necessarily money available for personal purchases.
How to Manage Business Finance as a Beginner
A complicated financial dashboard isn’t necessary on day one.
Start with the essentials.
Track Every Important Transaction
Record sales, expenses, payments, refunds, and outstanding invoices accurately.
Use suitable accounting software or an organized system appropriate to your business.
Monitor Cash Regularly
Understand the money currently available and payments coming due.
A cash forecast can help identify shortages before they become emergencies.
Separate Fixed and Variable Costs
Fixed costs may include regular rent or software subscriptions.
Variable costs can change with sales volume, such as certain packaging or fulfillment expenses.
Understanding the difference helps with pricing and planning.
Build a Cash Reserve When Possible
Unexpected repairs, delayed customer payments, or temporary sales declines can disrupt operations.
The right reserve depends on the business’s risks and cash flow patterns.
Review Profit Margins
High revenue isn’t enough.
Understand how much remains after direct costs and operating expenses.
Evaluate Debt Carefully
Before borrowing, identify what the money will accomplish and how repayment will be funded.
Don’t assume that future growth will automatically cover every obligation.
The 30-Day Business Finance Starter Plan
Here’s a practical roadmap for a small business owner.
Week 1: Organize the numbers. Record sales, expenses, debts, cash balances, and amounts owed by customers.
Week 2: Understand profitability. Prepare a simplified income statement and identify your main cost drivers.
Week 3: Forecast cash. List expected incoming payments and outgoing obligations for the next several weeks.
Week 4: Review decisions. Identify one action that could improve your financial position, such as reducing unnecessary expenses, improving invoice collection, reviewing prices, or negotiating suitable supplier terms.
The goal isn’t to transform your business into a multinational corporation.
It’s to make sure financial decisions are based on information rather than guesswork.
Common Business Finance Mistakes
Even experienced entrepreneurs can make avoidable financial errors.
Confusing revenue with profit. Sales figures don’t reveal whether the company is actually earning money after expenses.
Ignoring cash flow. Outstanding invoices cannot always pay bills that are due today.
Borrowing without a repayment plan. Financing creates obligations regardless of whether projected sales materialize.
Growing too quickly. Expansion can increase inventory, payroll, and operating costs before cash collections catch up.
Underpricing products. A price that covers manufacturing but ignores marketing, shipping, returns, and overhead may be unsustainable.
Mixing business and personal funds. Poor separation can make financial reporting and decision-making more difficult.
Making decisions without forecasts. A little preparation won’t eliminate uncertainty, but it can make risks more visible.
Frequently Asked Questions
What is business finance in simple words?
Business finance is the process of obtaining, managing, and using money to operate a business, invest in growth, and meet financial obligations.
What are the main types of business finance?
The main decision areas include financing, investment, and working capital management. Common funding types include debt financing, equity financing, and internally generated funds.
Why is business finance important?
It helps companies pay expenses, understand profitability, manage cash flow, evaluate investments, and make responsible growth decisions.
What is an example of business finance?
A company comparing the cost of borrowing $50,000 against the expected benefits of purchasing new equipment is making a business finance decision.
What is the difference between debt and equity finance?
Debt financing involves borrowing with repayment obligations. Equity financing involves raising capital by selling an ownership interest.
Can a profitable company run out of money?
Yes. A business can report accounting profits while experiencing a cash shortage because customers haven’t paid yet or because other cash obligations arise before receipts.
Is business finance the same as accounting?
No. Accounting records and reports financial activity, while business finance focuses on using financial information to guide funding, investment, cash management, and risk decisions.
Do small businesses need financial planning?
Yes. Even a very small business benefits from understanding income, expenses, cash availability, financial obligations, and future funding needs.
What is the best source of business finance?
There is no universal best source. The appropriate choice depends on business maturity, financial strength, capital requirements, cost, repayment capacity, and ownership preferences.
Final Thoughts
Business finance doesn’t need to sound complicated.
At its heart, it’s about making sure a company has enough money to operate today while making sensible decisions about tomorrow.
A business needs to understand its costs.
It needs to know when customers will pay.
It needs to decide whether borrowing is worthwhile, whether expansion makes sense, and whether its financial position can withstand unexpected problems.
And here’s something worth remembering.
A company can have beautiful branding, enthusiastic customers, and impressive sales figures while still facing serious financial difficulties.
Those things are valuable, but they don’t replace financial discipline.
Disclaimer
At Weird Wealth, we’re interested in creative business ideas and unconventional income opportunities. Yet the difference between a temporary earning experiment and a sustainable business often comes down to what happens after the first sale.
Making money gets a business started. Understanding and managing that money gives the business a better chance of lasting.