Saving money has a terrible public-relations problem. It sounds like skipping restaurants, cancelling everything fun, buying the cheapest version of everything and staring sadly at your bank balance while everyone else enjoys themselves.
It doesn’t have to work that way. The smarter approach is not to make your entire life cheaper. It’s to make bad spending less automatic and make your important spending more intentional.
You can spend generously on things you genuinely value while cutting the purchases you barely notice. That’s the difference between being cheap and being financially organized.
Key Takeaways
- Saving money works better when you change expensive habits rather than eliminate every enjoyable expense.
- Tracking actual spending reveals where money is quietly disappearing.
- Automating savings removes some of the decision-making from the process.
- Cutting recurring costs can matter more than obsessing over tiny daily purchases.
- The goal isn’t to spend nothing; it’s to make more of your money serve your priorities.
1. Find Your Three Biggest Money Leaks
Don’t start by worrying about a $4 coffee. Open your bank and card statements and look at the last few months. Where did the largest amounts actually go?
Maybe it’s delivery. Maybe it’s subscriptions. Maybe it’s shopping. Maybe it’s transportation. Maybe it’s expensive financing.
The CFPB recommends looking at actual account and card history when assessing spending because a realistic picture is more useful than a budget based on what you think you spend. Fixing three large leaks can be far more meaningful than eliminating dozens of tiny purchases.
2. Cancel Subscriptions You Forgot Existed
Streaming services are obvious. But check everything. Cloud storage. Apps. Newsletters. Fitness memberships. Software.
Gaming services. Premium banking features. You don’t need to cancel everything.
Just ask:
“Did I use this enough last month to justify paying for it?” If the answer is no, cancel it.
3. Create a “Wait 48 Hours” Rule
Impulse purchases feel urgent. Most aren’t. For anything non-essential above an amount you choose, wait 48 hours before buying it.
You may still buy it. That’s fine. The point isn’t to ban spending. It’s to separate wanting something from automatically purchasing it.
4. Make Your Savings Automatic
Saving whatever happens to be left at the end of the month is a surprisingly fragile strategy. There may be nothing left.
An automatic transfer reverses the order:
Income → savings → spending
The CFPB specifically recommends recurring transfers as one way to make saving consistent. Choose an amount that fits your actual cash flow rather than setting an unrealistic target and constantly reversing the transfer.
5. Stop Paying for Convenience You Don’t Value
Convenience isn’t bad. It’s expensive when you pay for it without noticing.
- Delivery fees.
- Rush shipping.
- Ride-hailing instead of walking.
- Pre-cut food.
- Daily takeaway.
Premium versions of services you barely use.
The question isn’t:
“Can I eliminate convenience?”
It’s:
“Which conveniences are actually worth paying for?” Keep those. Remove the rest.
6. Give Every Expense a Job
Instead of asking whether something is cheap, ask what it does for you. A $100 purchase that you use every day may be better value than a $20 purchase you never use.
A $15 meal with friends may have more value to you than $5 of snacks bought randomly throughout the week. Money becomes easier to manage when spending reflects priorities.
7. Build a Grocery List Before You Shop
Food spending gets expensive when every shopping trip becomes improvisation. Plan a few meals. Check what you already have. Write the list. Then shop.
You don’t need to become obsessed with coupons. You simply need fewer moments where you’re standing in a supermarket thinking: “I don’t know what I’m buying, but somehow this basket is full.”
8. Use What You Already Own
Before buying something new, check your home.
You may already own:
- Clothes you haven’t worn
- Unused electronics
- Kitchen equipment
- Books
- Exercise equipment
- Tools
- Accessories
- Furniture
Sometimes the cheapest version of a purchase is the thing you already paid for.
9. Sell the Stuff You Don’t Use
This one has a double benefit.
You create cash while reducing clutter.
- Old phones.
- Cameras.
- Furniture.
- Gaming equipment.
- Clothes.
- Collectibles.
- Tools.
Unused appliances. Don’t think of everything as junk. Somebody else may have a reason to pay for it. And the money can go directly toward savings or another financial goal.
10. Compare the Total Cost, Not the Sticker Price
A cheap product isn’t necessarily cheap.
Look at:
- Purchase price
- Maintenance
- Repairs
- Accessories
- Financing
- Replacement frequency
- Energy use
- Resale value
This matters particularly for cars, electronics, appliances and other expensive purchases. The real price is what the item costs you over its useful life.
11. Negotiate Recurring Bills
Some expenses deserve a phone call.
- Internet.
- Insurance.
- Phone plans.
- Business services.
- Software.
- Memberships.
Ask whether there is a cheaper plan, promotional rate or alternative package. You won’t always get one. But unlike skipping a coffee, a successful reduction in a recurring bill can keep saving you money month after month.
12. Make a “Fun Money” Budget
This sounds strange for a saving article. It’s actually one of the most useful ideas. Give yourself money you’re allowed to spend without guilt.
Once that money is gone, you’re done until the next period. This creates a boundary without turning every purchase into a moral debate. A budget should help you control money. It shouldn’t make you afraid to use it.
13. Don’t Upgrade Just Because You Can
Your phone works. Your laptop works. Your car works. Your furniture works. Then the new version appears. Suddenly the old one feels embarrassing. That’s marketing doing its job.
Upgrade when the new product solves a real problem—not simply because the manufacturer released another model.
14. Learn the Difference Between Price and Value
Sometimes spending more is the smarter decision. A cheap pair of shoes that needs replacing repeatedly may cost more over time than a durable pair. A poor laptop that wastes hours may be more expensive than a reliable machine.
A bad office chair can become a daily source of frustration. Saving money isn’t about buying the cheapest thing. It’s about getting more useful value from every dollar.
15. Use a Separate Emergency Fund
Your normal checking balance shouldn’t have to handle every financial surprise. A dedicated emergency fund can help cover unexpected expenses such as repairs, medical bills or loss of income without immediately turning to credit or loans. The right amount depends on your circumstances. Start with something achievable. Then build it.
16. Make “Unexpected” Expenses Expected
Some expenses aren’t actually surprises. Car maintenance. Insurance. Annual memberships. School expenses. Birthdays. Holidays.
Property maintenance. They may not happen every month, but you know they exist. Put them into your financial plan before they arrive.
The CFPB recommends accounting for less-frequent expenses rather than pretending a monthly budget contains only perfectly predictable bills.
17. Have a No-Spend Day
Pick one day each week when you don’t buy anything unnecessary.
- No shopping.
- No food delivery.
- No random online purchases.
- No convenience spending.
It’s less about the money saved that day and more about noticing how often you normally spend without thinking.
18. Make Your Home Cheaper to Live In
Look at recurring household costs. Energy. Water. Internet. Maintenance. Cleaning products. Food waste.
Small improvements can compound over time. The goal isn’t to live uncomfortably. It’s to stop paying for waste.
19. Cook the Meals You Actually Like
People often try to save money by planning meals they don’t enjoy. Then they order something else.
Instead, build a short list of inexpensive meals you genuinely like. Five reliable meals can be more useful than an ambitious 30-day meal plan that collapses after four days.
20. Use a “One In, One Out” Rule
Buying clothes?
One old item leaves.
Buying kitchen equipment?
Sell or donate something you don’t use.
Buying electronics?
Consider whether an existing device can be sold. The rule limits accumulation and can turn old purchases into partial funding for new ones.
21. Make Your Budget Boring
A good financial system doesn’t need to be complicated.
You need to know:
- Income
- Fixed expenses
- Flexible expenses
- Debt
- Savings
- Investments
- Money left over
The CFPB’s budgeting guidance similarly emphasizes identifying income, tracking spending and creating a realistic working budget. If your system takes two hours every week to maintain, you’re less likely to maintain it.
22. Create a “Money Rules” List
Instead of making hundreds of decisions, create a few rules.
For example:
- Wait 48 hours before major discretionary purchases.
- Save automatically after payday.
- Don’t carry unnecessary subscriptions.
- Check recurring bills every few months.
- Don’t finance something simply because the monthly payment looks small.
- Keep an emergency reserve.
- Increase savings when income increases.
Rules reduce decision fatigue.
23. Save Part of Every Unexpected Dollar
Bonus. Gift. Refund. Side-hustle payment. Freelance project. Unexpected cash. You don’t have to save all of it.
But saving a defined portion prevents lifestyle inflation from swallowing every increase in income. A small saving habit can also make irregular income easier to manage over time. CFPB guidance notes that consistent contributions, even when small, can help build savings.
24. Don’t Let Lifestyle Inflation Eat Your Raises
You earn more. Then you upgrade everything. Better phone. Better car. Better apartment. More restaurants. More subscriptions. More shopping.
Eventually, your income increased but your financial position barely changed. When your income rises, increase your lifestyle deliberately. Don’t let it happen automatically.
25. Turn Savings Into an Asset
This is where saving becomes more interesting. Saving isn’t the final destination. It’s the first layer. You build cash reserves. Then, depending on your circumstances and financial goals, money can eventually be directed toward longer-term goals or investments.
The objective is to move from:
Earn → Spend → Repeat
toward:
Earn → Save → Protect → Invest → Build
That’s the beginning of wealth-building behavior.
The “Save Without Suffering” Framework
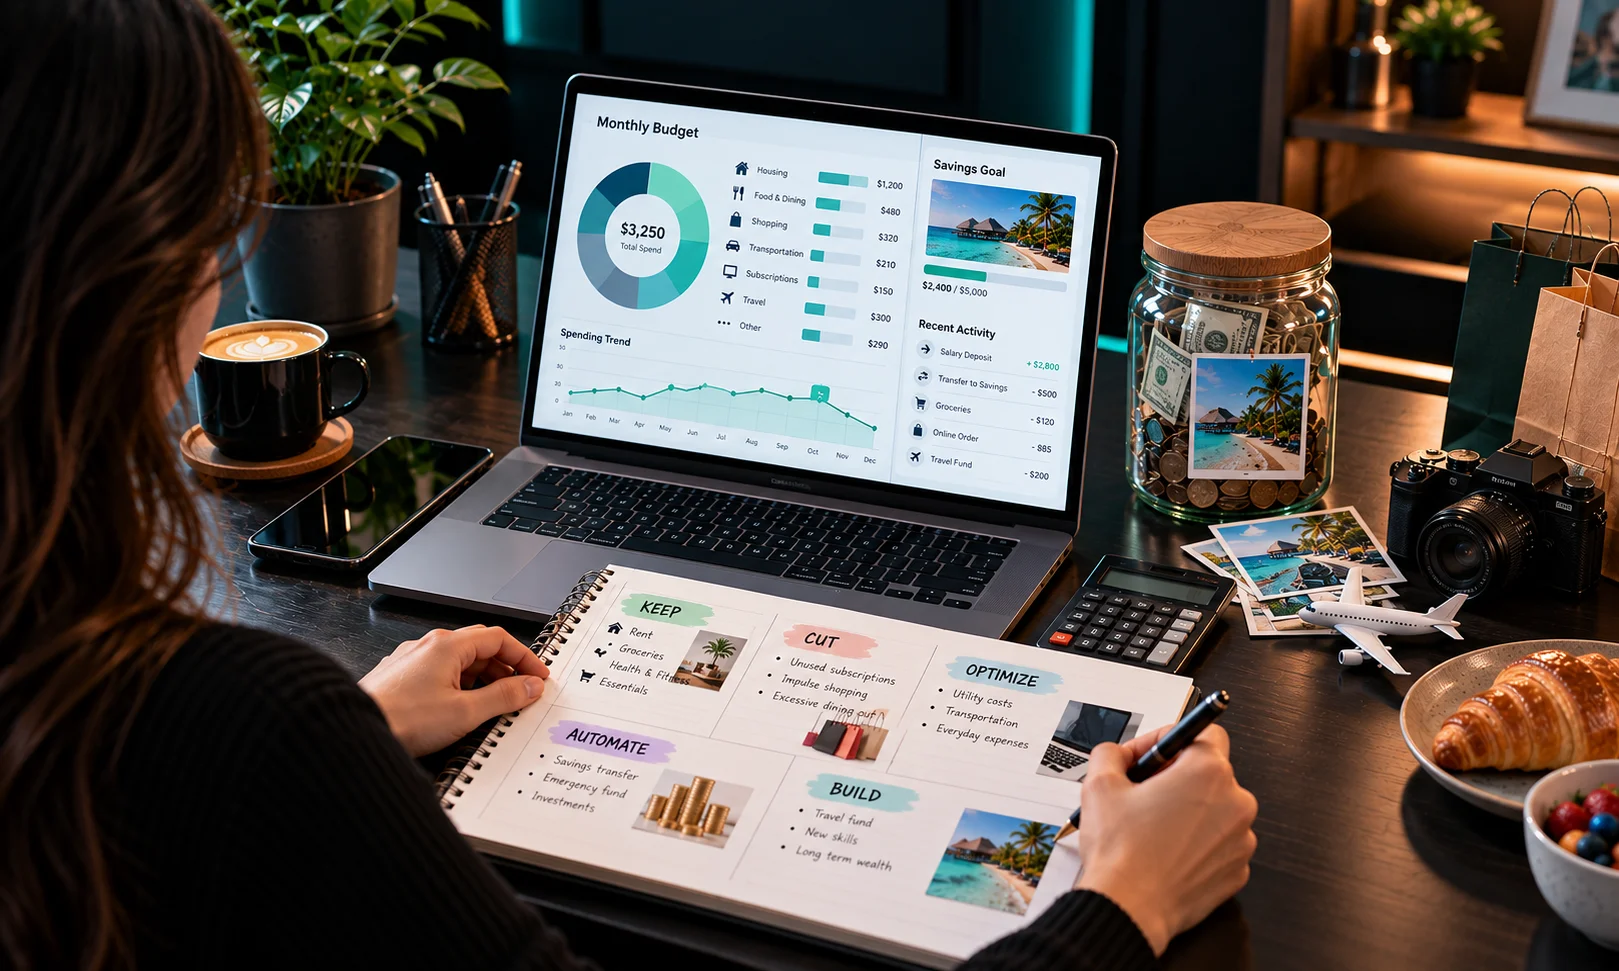
Use five categories.
| Category | Question |
| Keep | What spending genuinely improves my life? |
| Cut | What am I paying for but barely using? |
| Optimize | Which recurring costs can I reduce? |
| Automate | What can move into savings automatically? |
| Build | Where should surplus money eventually go? |
This is much more sustainable than trying to cut everything.
What Should You Cut First?
Start with expenses that are:
Large + recurring + low value.
For example:
| Expense | Frequency | Personal value | First question |
| Unused subscription | Monthly | Low | Cancel it? |
| Expensive phone plan | Monthly | Medium | Can it be cheaper? |
| Frequent delivery | Weekly | Low/Medium | Can I reduce it? |
| Car payment | Monthly | High | Is the total cost sustainable? |
| Daily coffee | Daily | High for some | Is it actually a problem? |
Notice the last row. A $5 coffee isn’t automatically your financial enemy. If it’s something you genuinely enjoy and larger expenses are under control, attacking the coffee may be completely the wrong priority.
Saving Money Should Buy You Something
This is the part people forget.Saving isn’t supposed to be an endless punishment. The money should eventually create something: An emergency reserve. A debt-free balance sheet. A business.
An investment portfolio. A home. A travel fund. More freedom. More options. More security. A good financial system makes your money more useful.
The Weird Wealth Read
The goal isn’t to become the person who refuses to spend $3. It’s to become the person who knows why they’re spending $3. You don’t need to eliminate every pleasure. You need to stop financing things you don’t care about.
You don’t need to track every cent forever. You need to understand where the big money is going. You don’t need to make saving miserable. You need to make good financial behavior automatic enough tha it doesn’t require constant willpower.
Because the real trick to saving money isn’t spending anything. It’s spending intentionally enough that the money you keep can eventually do something bigger.