Imagine opening your banking app and receiving an alert about a suspicious payment, getting an instant answer to a routine question, or completing a loan application without filling out the same information multiple times. These experiences illustrate how AI in banking is changing the way financial institutions serve customers and manage risk.
Banks are using artificial intelligence to analyze transactions, detect potential fraud, automate customer support, process documents, and assist with lending decisions. The technology can help financial institutions handle large volumes of information more efficiently, but it also introduces challenges involving privacy, fairness, security, and accountability.
Understanding how AI works in banking helps consumers recognize its benefits, question automated decisions when necessary, and make more informed choices about the financial services they use.
Key Takeaways
- AI helps banks identify suspicious transactions, automate routine tasks, and improve customer service.
- Machine learning can support credit assessment, risk analysis, and operational forecasting.
- AI-powered banking tools can make services more responsive, but they can also produce incorrect results.
- Data privacy, algorithmic bias, cybersecurity, and transparency are important concerns.
- AI should support responsible banking decisions rather than replace necessary human oversight.
What Is AI in Banking?
AI in banking refers to the use of artificial intelligence technologies to support or automate banking activities. These technologies can analyze transaction data, recognize patterns, interpret customer questions, and help employees make decisions.
Traditional banking software often relies on predefined rules. AI systems can use statistical models and machine learning to identify patterns in data that may be difficult to capture through simple rules alone.
For example, a bank may use an AI model to examine transaction behavior and flag payments that appear inconsistent with a customer’s usual activity. The bank can then apply additional checks before deciding whether the transaction is legitimate.
AI does not necessarily make the final decision. Depending on the application, it may generate an alert, recommend an action, prepare information for an employee, or automate a limited process.
How Banks Use Artificial Intelligence
1. Fraud Detection and Prevention
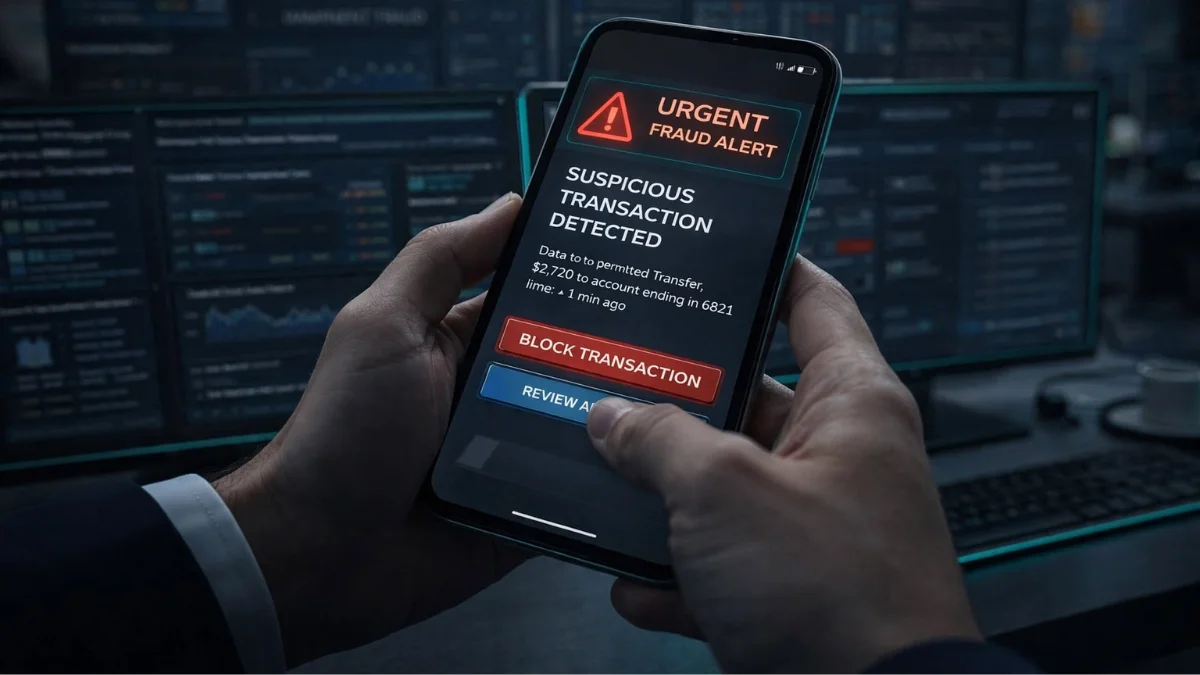
Fraud detection is one of the most important applications of AI in banking.
Banks process large numbers of payments, transfers, card transactions, and account activities. AI models can evaluate patterns and identify transactions that may require closer inspection.
For example, a system might flag an unusual payment based on a combination of transaction size, device information, location signals, and previous activity.
When a transaction appears suspicious, the bank may request additional verification, temporarily restrict the payment, or refer the case to a fraud investigation team.
AI can also help identify relationships between suspicious transactions across multiple accounts.
However, an unusual transaction is not necessarily fraudulent. A legitimate purchase while traveling or a sudden change in spending habits may trigger a false alert. Banks must balance fraud prevention with convenient access to customers’ money.
2. AI-Powered Customer Service
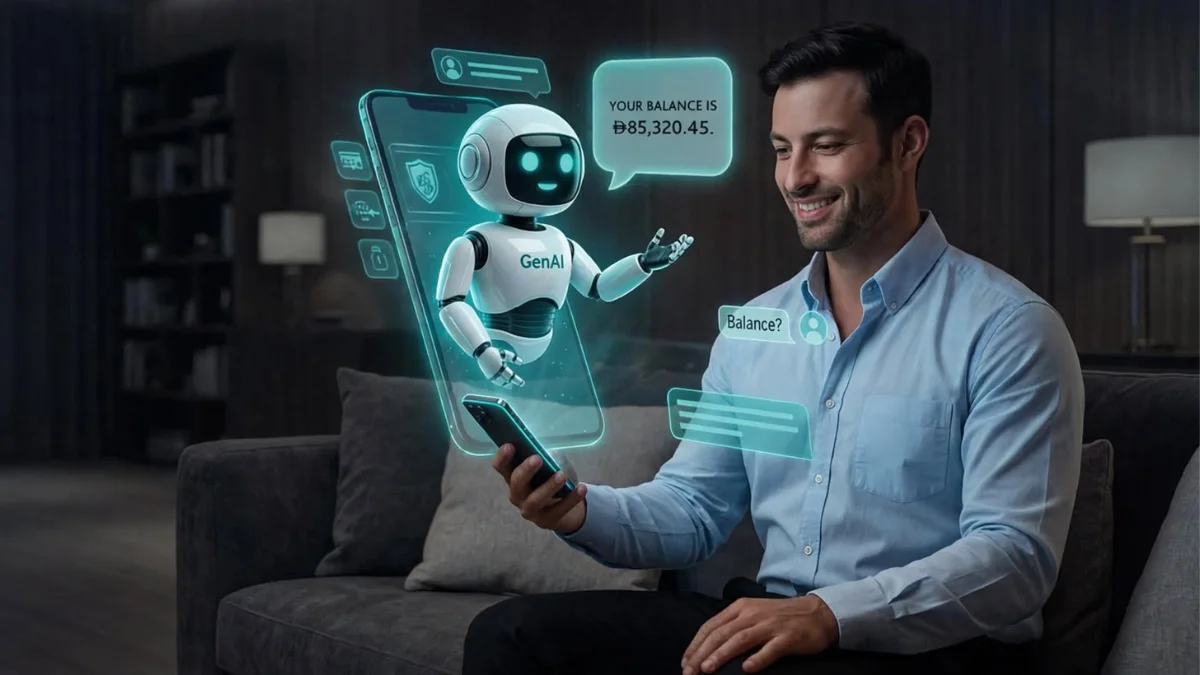
Many banks use chatbots and virtual assistants to handle routine customer inquiries.
Customers may ask about account balances, transaction status, payment procedures, card controls, or general banking services. An AI assistant can interpret the question and provide an answer or direct the customer to the appropriate service.
More advanced systems can help customer-service employees summarize previous interactions and retrieve relevant information.
The benefits include faster responses and support outside traditional service hours. However, AI assistants may misunderstand questions or provide incomplete information.
For complicated matters such as disputed payments, suspected identity theft, or account restrictions, customers should have access to a human representative.
3. Credit Assessment and Loan Processing
When a customer applies for a loan, a bank must assess the application and evaluate the likelihood of repayment.
AI can help process application documents, identify missing information, detect inconsistencies, and analyze permitted financial data. Some models also support credit-risk assessment.
Automation may reduce repetitive work and help employees review applications more efficiently.
Nevertheless, lending decisions require careful oversight. An AI model may rely on flawed historical data, reproduce existing inequalities, or produce a result that is difficult to explain.
Banks need appropriate safeguards to ensure that decisions comply with applicable rules and that customers can correct inaccurate information or challenge decisions through available procedures.
4. Personalized Banking Services
AI can help banks organize customer information and identify patterns that may be useful for relevant services.
For example, a banking application might categorize spending, summarize recurring payments, or notify a customer that a bill is approaching.
Some systems may also suggest financial products based on customer information and stated needs.
Personalization can be helpful, but it should not become intrusive. Customers should understand how their data is being used, and recommendations should not be mistaken for independent financial advice.
5. Document Processing and Back-Office Automation
Banks handle applications, identification documents, invoices, contracts, statements, and compliance records. AI can help extract information from these documents, classify them, and route them to the appropriate department.
This can reduce manual data entry and speed up certain workflows.
For example, a document-processing system may identify missing fields in an application or extract relevant details for an employee to review.
Automation still requires quality checks. A system may misread a document, overlook an exception, or classify information incorrectly. Human review remains important when errors could affect customers or regulatory reporting.
6. Anti-Money Laundering and Compliance Monitoring
Banks must monitor activity for potential financial crime and comply with applicable reporting requirements.
AI can support transaction monitoring by identifying unusual patterns, grouping related alerts, and helping investigators prioritize cases.
These tools can assist compliance teams in managing large amounts of information, but an alert is not proof of wrongdoing.
Effective systems require appropriate thresholds, investigation procedures, documentation, and oversight. Excessive false positives can waste resources and inconvenience legitimate customers.
7. Risk Management and Financial Forecasting
Banks must manage credit exposure, liquidity, operational risks, and changing market conditions.
AI models can help analyze historical data, identify emerging patterns, and evaluate possible scenarios. These insights may support decisions about risk monitoring, resource allocation, and financial planning.
However, historical patterns do not always predict future events. An unexpected economic shock or a change in customer behavior can make a model less reliable.
AI-based forecasts should therefore be combined with established risk-management practices, scenario analysis, and professional judgment.
Benefits of AI in Banking
AI can improve certain banking processes when the technology is well designed and properly monitored.
| Benefit | Banking application | Important limitation |
| Faster processing | Document review and routine workflows | Complex cases may still require manual work |
| Fraud monitoring | Identifying unusual transactions | Legitimate payments can be flagged |
| Customer support | Chatbots and virtual assistants | Responses can be incomplete or incorrect |
| Risk analysis | Credit and operational risk assessment | Models depend on data quality |
| Personalization | Spending summaries and relevant service suggestions | May raise privacy concerns |
| Operational efficiency | Automating repetitive tasks | Implementation and monitoring have costs |
| Compliance support | Organizing alerts and identifying patterns | AI cannot replace all investigative judgment |
The strongest applications usually address a specific problem and include safeguards for cases the system cannot handle reliably.
Risks and Challenges of AI in Banking
Data Privacy and Confidentiality
Banking information can reveal income, spending habits, debts, transfers, and personal relationships.
AI systems that process this information need appropriate controls over collection, access, storage, sharing, and retention.
Customers should be cautious about entering account information or uploading bank statements into unverified AI tools. Banks should clearly explain how customer information is used and protect it against unauthorized access.
Algorithmic Bias in Lending
AI models can produce unfair outcomes if their training data, design, or evaluation methods contain biases.
In lending, this could affect how applications are assessed or how creditworthiness is estimated.
Banks should test models for discriminatory outcomes, evaluate the relevance of the information used, and provide appropriate processes for review and correction.
Cybersecurity Threats
AI can strengthen security monitoring, but criminals can also use AI to create convincing phishing messages, imitate voices, and automate fraud attempts.
A message that appears to come from a bank employee should not automatically be trusted. Customers should use verified communication channels and never disclose passwords, one-time authentication codes, or wallet recovery phrases in response to unsolicited requests.
Banks must also protect their own AI systems against unauthorized access, manipulated inputs, and data leakage.
Incorrect AI Decisions
An AI system can misunderstand a customer’s request, misclassify a transaction, or produce an inaccurate recommendation.
These errors can have serious consequences if they affect account access, payment processing, or lending decisions.
Banks need testing, monitoring, escalation procedures, and appropriate human review for high-impact decisions.
Lack of Transparency
Some AI systems are difficult to explain, particularly when they use complex models.
Customers may struggle to understand why a payment was flagged or a loan application was declined. Financial institutions should provide clear explanations where required and make suitable review or complaint channels available.
Overdependence on Automation
Automating too many decisions without effective supervision can make a bank less responsive when unusual situations arise.
Employees need the training and authority to investigate exceptions rather than relying blindly on automated recommendations.
Traditional Banking vs. AI-Enabled Banking
AI does not create an entirely separate type of banking. Instead, it changes how some existing services are delivered.
| Area | Traditional approach | AI-enabled approach |
| Fraud detection | Rules and manual investigation | Rules combined with pattern-recognition models |
| Customer support | Phone, branch, and human-assisted service | Human service plus automated assistants |
| Document review | Manual extraction and verification | Automated extraction with quality checks |
| Credit assessment | Established scoring methods and human review | Existing methods supplemented by AI models |
| Financial forecasting | Statistical analysis and expert judgment | Additional pattern analysis and predictive models |
| Compliance monitoring | Rules, alerts, and investigator review | AI-supported alert prioritization and pattern analysis |
The comparison is not absolute. Traditional banking already uses sophisticated software, and AI-enabled systems still rely on rules, employees, and established controls.
How AI Is Changing Digital Banking
Digital banking allows customers to manage many financial activities through websites and mobile applications. AI can make these experiences more responsive by supporting automated assistance, transaction categorization, and suspicious-activity alerts.
For customers, the most noticeable changes may include:
- More responsive answers to routine banking questions.
- Notifications about unusual account activity.
- Automatic summaries of spending and recurring payments.
- Faster processing of certain applications and documents.
- More personalized financial information.
These features differ by bank, product, and country. Not every institution offers the same capabilities, and an AI-powered interface does not automatically mean that every underlying process uses artificial intelligence.
Customers should continue to review transactions, protect their login credentials, and contact their bank through official channels when something appears wrong.
How to Evaluate an AI-Powered Banking Service
Before relying on a banking assistant or connecting financial data to an AI tool, consider five questions.
- Is the provider legitimate?
Confirm that you are using the bank’s official application or website. Be wary of unfamiliar services that request banking credentials without a clear reason.
- What data does the service access?
Review the information required and understand whether the service can access account balances, transactions, identity documents, or other sensitive data.
- Can you verify its output?
Check important information against original statements, transaction records, and official bank communications.
- Can you reach a person?
For disputed transactions, denied access, or important financial decisions, look for an effective way to contact a human representative.
- What happens if the system is wrong?
Understand how to report errors, correct information, challenge a decision, or request additional review.
These questions help distinguish a useful banking feature from a service that introduces unnecessary risk.
The Future of AI in Banking
AI is likely to play a continuing role in fraud monitoring, customer support, document processing, risk analysis, and digital banking.
One developing area is agentic AI, in which systems can perform multiple steps toward a goal. In banking, this could eventually support workflows such as gathering documents, preparing application information, or helping customers organize financial tasks. AI is also changing how people explore income opportunities, from mystery shopper jobs to finding practical ways to rent out your car.
Greater autonomy also increases the importance of controls. A system that can initiate actions needs clear permissions, transaction limits, monitoring, and safeguards against unintended activity.
Banks will also need to evaluate the reliability of their models, protect sensitive information, and maintain accountability for decisions that affect customers.
The long-term value of AI in banking will depend not only on automation but also on trust. Customers need services that are secure, understandable, and fair. For individuals managing their finances, maintaining an emergency fund can also provide a useful safety net for unexpected expenses.
Frequently Asked Questions
What is AI in banking used for?
AI in banking is used for fraud detection, customer service, credit assessment, document processing, compliance monitoring, personalized banking, and risk management.
How does AI detect banking fraud?
AI systems can analyze transaction patterns and other permitted signals to identify activity that differs from expected behavior. Banks may use the resulting alerts to request verification or investigate a transaction. An alert alone does not prove fraud.
Can AI approve a bank loan?
Some banks use AI to support or automate parts of the lending process. The exact role of AI depends on the institution, product, and applicable rules. Automated decisions should be subject to appropriate controls and review procedures.
Is AI banking safe?
AI can support security, but it also introduces risks involving privacy, cyberattacks, inaccurate decisions, and bias. Customers should use official banking channels, protect their credentials, and review account activity regularly.
Will AI replace bank employees?
AI may automate some repetitive tasks and change how banking employees work. However, complex customer issues, accountability, risk decisions, and exception handling still require human judgment in many situations. The impact will vary by role and institution.
Does every digital bank use AI?
No. Digital banking describes how financial services are delivered, while AI describes a set of technologies. A digital bank may use AI for selected tasks, but not every digital banking service relies on it.
Can AI manage my bank account automatically?
Some services may automate limited financial tasks, depending on the permissions granted and the provider’s capabilities. Before enabling automation, understand what actions it can take, what approvals are required, and how to stop or reverse an action where possible.
Final Thoughts
AI in banking is helping financial institutions process information, monitor suspicious activity, assist customers, and automate selected workflows. These applications can improve efficiency and support better-informed decisions, but they are not free from errors or risks.
For customers, the most important priorities remain protecting account credentials, reviewing transactions, understanding how personal information is used, and questioning decisions that appear incorrect. For banks, responsible AI adoption requires strong security, fair and transparent processes, effective monitoring, and meaningful human oversight.
AI can improve banking when it serves customers reliably. Trust must remain at the center of every financial decision.
Financial disclaimer:
This article is for general informational and educational purposes only and is not personalized financial, legal, or investment advice. AI-enabled banking features and consumer protections vary by provider and jurisdiction. Verify important information directly with your financial institution.