Imagine applying for a loan and receiving a decision based on hundreds of pieces of financial information rather than a handful of traditional indicators. A lender might use automated systems to review income, payment history, existing debt, and other permitted data before deciding whether an application requires further assessment.
This is where AI lending and credit scoring come into the picture. Financial institutions can use artificial intelligence to process applications, estimate repayment risk, identify inconsistent information, and support lending decisions.
These technologies can make certain processes faster, but they also raise important questions. How does an AI system assess a borrower? Can it make credit decisions unfairly? And what happens when a model gets something wrong?
Understanding the technology helps borrowers make sense of automated lending while helping businesses evaluate its opportunities and limitations.
Key Takeaways
- AI lending uses artificial intelligence to support loan applications, underwriting, fraud checks, and credit-risk assessment.
- AI credit scoring can analyze permitted financial information to estimate the likelihood that a borrower will repay a loan.
- Automated systems may improve processing speed, but they do not guarantee loan approval or more accurate decisions.
- Data quality, algorithmic bias, privacy, and explainability are major concerns.
- Borrowers should review their credit information and ask lenders how to correct inaccurate details or challenge a decision.
What Is AI Lending?
AI lending refers to the use of artificial intelligence and related analytical technologies throughout the lending process.
A lender may use AI to extract information from applications, identify missing documents, detect inconsistencies, estimate credit risk, or help employees review loan requests.
Traditional lending systems often rely on predefined rules and established credit-scoring methods. AI-based systems can also identify patterns across larger datasets and use those patterns to estimate potential repayment risk.
For example, a lender might use a model to assess whether an applicant’s financial information resembles patterns associated with borrowers who repaid previous loans. The result may help determine whether the application needs additional verification or human review.
AI does not automatically replace the lender’s policies or legal responsibilities. The institution remains responsible for ensuring that its lending process meets applicable requirements.
What Is AI Credit Scoring?
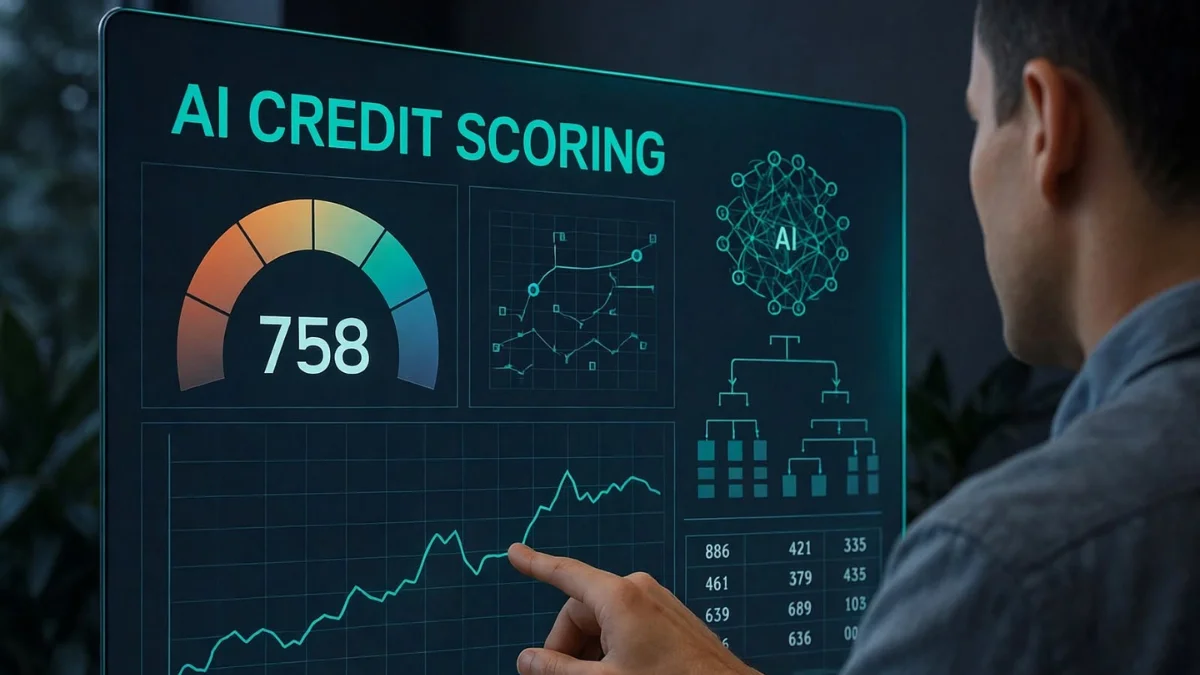
AI credit scoring uses artificial intelligence or machine-learning techniques to help estimate a borrower’s creditworthiness.
Creditworthiness generally refers to the likelihood that someone will meet their repayment obligations. Depending on the lender and jurisdiction, an assessment may consider factors such as payment history, outstanding debt, income, and other permitted information.
An AI model may examine relationships among these variables that a simpler scoring system does not capture.
For example, two applicants might have similar incomes but different existing debt obligations and repayment histories. A model could evaluate these differences when estimating repayment risk.
However, an AI-generated risk score is not a guarantee of future behavior. People can experience unexpected expenses, job changes, or other circumstances that affect their ability to repay.
It is also important to distinguish between an AI credit-risk model and a traditional credit score. Some lenders use AI to support established scoring systems, while others may use machine learning in particular parts of underwriting. Not every automated credit decision is powered by AI.
How AI Lending Works
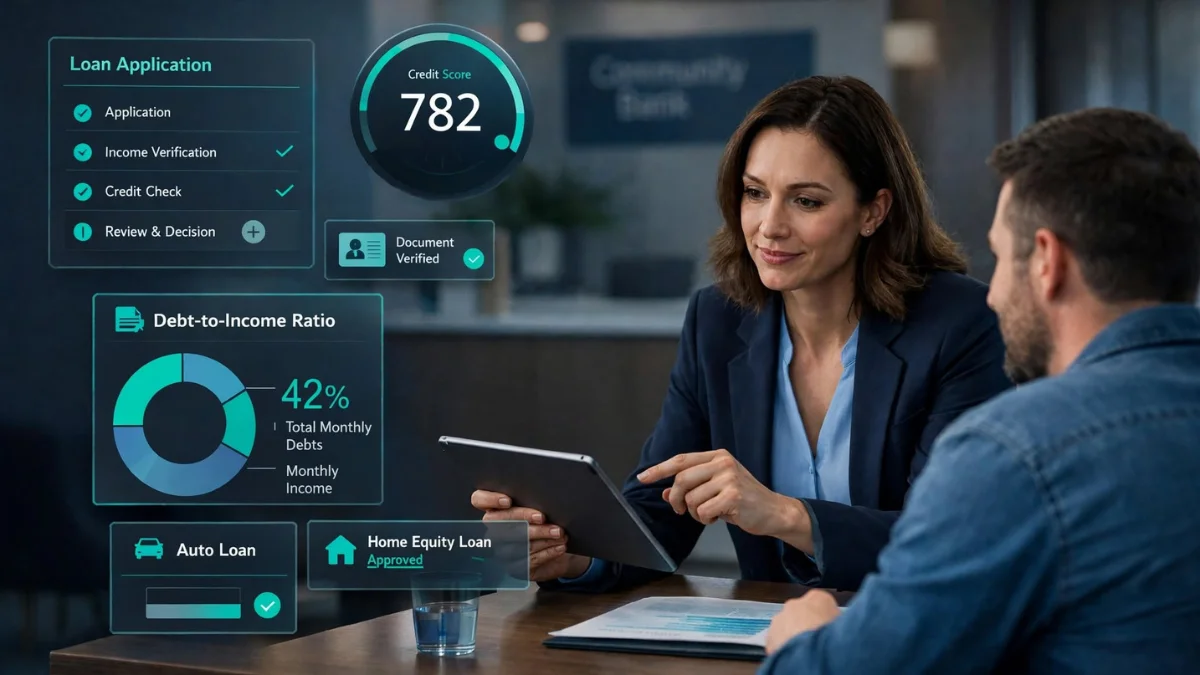
AI-supported lending typically involves several stages.
1. Collecting Application Information
The lender gathers information relevant to the loan application, such as identity details, income documentation, existing obligations, and repayment history.
The information collected depends on the type of loan, the lender’s policies, and applicable laws.
Accurate information is essential. Missing documents, outdated records, and incorrect identity details can affect the assessment.
2. Verifying Documents and Identity
AI tools can help extract information from uploaded documents, compare application details, and identify inconsistencies that may require additional checks.
For example, document-processing software may extract income figures from a statement and compare them with the information provided in an application.
Automated verification is not infallible. Poor-quality documents, unusual formats, and legitimate differences in records may lead to errors.
3. Assessing Credit Risk
The lender may use a credit score, a risk model, or a combination of analytical methods to estimate the likelihood of repayment.
An AI model might evaluate permitted information about debt obligations, repayment patterns, and other relevant financial factors.
The output can inform the underwriting process, but the lender may also consider eligibility requirements, loan affordability, collateral, and other factors.
4. Making or Supporting a Decision
Based on the application and relevant policies, the lender may approve the loan, decline it, request additional information, or send it for further review.
Some decisions can be automated, while others involve human underwriters.
The extent of AI involvement varies between institutions. A lender’s use of AI does not necessarily mean that a model independently determines the final outcome.
5. Monitoring Performance
Lenders may evaluate whether their models continue to estimate risk accurately as economic conditions and borrower behavior change.
They can compare predictions with actual repayment outcomes, investigate unusual patterns, and update models when necessary.
Monitoring is important because a system that performed well on historical data may become less reliable under different conditions.
Benefits of AI Lending and Credit Scoring
Faster Application Processing
Automated document extraction and data analysis can reduce repetitive work. This may help lenders process straightforward applications more quickly.
However, complex applications or cases requiring additional verification may still take considerable time.
More Efficient Risk Assessment
AI can help lenders analyze multiple variables and identify patterns that may be useful for evaluating repayment risk.
This can support underwriting teams, particularly when they need to review large numbers of applications.
Improved Fraud Screening
AI systems can help identify inconsistencies in application documents, suspicious identity information, or patterns associated with fraudulent applications.
A flagged application is not necessarily fraudulent. Legitimate discrepancies may require additional documentation rather than automatic rejection.
Potentially Broader Assessment
Some AI models may help lenders evaluate relevant information beyond a narrow set of traditional indicators, where such information is legally permitted and appropriate.
This could be useful for certain applicants whose financial circumstances are not fully represented by conventional credit histories.
However, using more information does not automatically make a model fairer or more accurate. Alternative data must be carefully evaluated for reliability, relevance, privacy, and potential bias.
Consistent Processing
Automated workflows can apply the same documented procedures across many applications.
Consistency can reduce certain forms of manual error, but only if the system itself is appropriately designed. A flawed model can apply an unfair or inaccurate process consistently.
AI Lending vs. Traditional Lending
| Feature | Traditional lending processes | AI-supported lending |
| Information processing | Manual review and established software | Automated extraction and analysis alongside existing systems |
| Credit assessment | Traditional scores, rules, and underwriting | May combine traditional methods with machine-learning models |
| Application handling | Human-led or rule-based workflows | Automation may reduce repetitive steps |
| Risk identification | Established indicators and manual investigation | Can identify additional patterns in suitable datasets |
| Explainability | Rules may be relatively straightforward to describe | Some models may be harder to interpret |
| Human involvement | Depends on the lender and loan type | May range from extensive review to limited intervention |
| Main risks | Manual errors and limitations of traditional data | Data errors, model bias, privacy risks, and opaque decisions |
The distinction is not absolute. Traditional lenders already use automated systems, and AI-supported lenders still rely on established rules, credit information, and human oversight.
Risks of AI Credit Scoring
AI can improve parts of the lending process, but its use in decisions about access to credit requires careful safeguards.
Algorithmic Bias
A model may learn patterns from historical lending data that reflect past inequalities or discriminatory practices.
If those patterns are reproduced, certain groups may receive less favorable outcomes even when the model does not explicitly use a protected characteristic.
Bias can also arise through variables that indirectly reflect sensitive characteristics or through data that does not represent the population being assessed.
Lenders need to test models for unfair outcomes and comply with applicable fair-lending and anti-discrimination requirements.
Inaccurate or Incomplete Data
An incorrect account record, outdated income figure, or mistaken identity match can affect an assessment.
AI does not automatically distinguish an inaccurate record from a reliable one. If incorrect information enters the system, the model may produce an unsuitable result.
Borrowers should review the information used in lending decisions where it is available and request corrections through the appropriate process.
Limited Explainability
Some machine-learning models produce scores through complex relationships that are difficult to explain in simple terms.
This can make it harder for borrowers to understand why an application was declined or why additional verification was required.
Lenders should maintain appropriate documentation and provide explanations or review procedures where required by law.
Privacy Concerns
AI credit scoring may involve sensitive information about income, spending, debts, and other financial circumstances.
Collecting more data can create additional privacy and security risks. Lenders should use appropriate information for legitimate purposes and protect it against unauthorized access.
Borrowers should be cautious about uploading financial statements or identity documents to unverified loan platforms.
Overreliance on Historical Patterns
Past repayment behavior does not fully determine a person’s future financial circumstances.
A model trained on historical data may be less reliable during economic shocks, major employment changes, or other situations that differ from its training environment.
Lenders should monitor model performance and avoid treating predictions as unquestionable facts.
Can AI Credit Scoring Help People With Limited Credit Histories?
People with limited credit histories may find it difficult to demonstrate their ability to repay a loan through conventional credit information alone.
In some circumstances, AI systems may help lenders evaluate additional permitted information that provides relevant evidence about financial stability or repayment capacity.
However, this approach has important limitations.
Alternative data may be incomplete, unreliable, or difficult to interpret. Certain variables may also introduce privacy concerns or unfairly disadvantage particular groups.
A responsible lending model should not assume that limited credit history automatically indicates high risk. Nor should it assume that additional data necessarily makes an applicant more creditworthy.
Whether AI improves access to credit depends on the quality of the information, the model’s design, the lender’s policies, and the protections available to borrowers.
How AI Lending Affects Borrowers
For consumers, AI lending may change how applications are processed and how financial information is evaluated.
Applicants may encounter automated document checks, digital identity verification, risk assessments, or decisions made with the support of machine-learning models.
To prepare for an application, consider these practical steps:
- Review your credit report where one is available.
- Check that your identity, income, and existing debt information are accurate.
- Keep relevant financial documents organized.
- Use official lender websites or verified applications.
- Ask what information is required and how it will be used.
- If your application is declined, request the reason and ask whether inaccurate information can be corrected or the decision reviewed.
Approval criteria vary by lender and jurisdiction. No AI tool can guarantee that an application will be approved.
How Businesses Can Implement AI Lending Responsibly
Financial institutions considering AI for underwriting or credit scoring need more than a technically effective model. They need a clear process for managing risk and accountability.
Define the Intended Use
Identify whether AI will support document processing, fraud checks, credit-risk estimates, or final lending decisions.
A model intended to organize documents has different risks from one that directly influences access to credit.
Validate the Data
Review whether the information is accurate, relevant, representative, and appropriate for the intended use.
Poor data quality can undermine model performance and create unfair outcomes.
Test for Accuracy and Fairness
Evaluate how the model performs across relevant borrower groups and under different economic conditions.
Testing should examine not only overall accuracy but also false rejections, missed risks, and potentially discriminatory outcomes.
Maintain Human Oversight
Establish procedures for reviewing unusual cases, correcting inaccurate records, and escalating decisions that require additional judgment.
Human involvement should be meaningful rather than a routine approval of automated results.
Monitor and Document Performance
Track model performance after deployment and document significant changes, limitations, and corrective actions.
Lenders should also maintain appropriate records to support compliance, auditing, and explanations of lending decisions.
AI Lending and Regulatory Considerations
Rules governing credit scoring, automated decisions, consumer privacy, and fair lending differ across countries and financial products.
A lender operating in one jurisdiction may face different obligations from a lender operating elsewhere. Requirements may also depend on whether the system is used to assess consumer loans, business financing, mortgages, or other credit products.
Organizations should determine which rules apply before deploying an AI lending system and review their obligations as regulations evolve.
Consumers should not assume that every lender provides the same explanation, appeal process, or data-access rights. These protections depend on the applicable legal framework.
Frequently Asked Questions
What is AI lending?
AI lending uses artificial intelligence to support tasks such as application processing, document verification, fraud screening, credit-risk assessment, and underwriting.
How does AI credit scoring work?
AI credit scoring analyzes permitted information to estimate a borrower’s credit risk. The model may identify patterns in repayment history, debt obligations, and other relevant variables. The exact information and methods depend on the lender and jurisdiction.
Can AI reject a loan application?
AI can influence lending decisions, and some processes may be automated. Whether a model can make or determine a particular decision depends on the lender’s system, policies, and applicable laws.
Is AI credit scoring more accurate than traditional scoring?
Not necessarily. AI may identify useful patterns that simpler systems miss, but it can also make mistakes, reflect biased data, or perform poorly when conditions change. Performance must be tested against an appropriate standard.
Can AI help people with no credit history?
Some lenders may use permitted alternative information to assess applicants with limited credit histories. Whether this improves access to credit depends on the data, model design, lending policies, and applicable regulations.
How can I challenge an AI-based lending decision?
Start by contacting the lender through its official channels. Ask for the reason for the decision, review the information used, and request corrections if records are inaccurate. Available review and complaint rights depend on the lender and jurisdiction.
Is AI lending safe?
AI can support efficient lending, but safety depends on data security, model quality, fairness testing, transparency, and appropriate oversight. Automated processing alone does not guarantee a fair or accurate decision.
Final Thoughts
AI lending and credit scoring are changing how financial institutions process applications and evaluate repayment risk. These technologies can reduce repetitive work, identify patterns, and support more efficient underwriting.
However, a model’s prediction is only as useful as the information, assumptions, and controls behind it. Biased data, inaccurate records, limited transparency, and overreliance on automation can create serious problems for borrowers.
The responsible use of AI in lending requires accurate information, regular testing, fair treatment, and meaningful ways to review mistakes. For borrowers, understanding how decisions are made and keeping financial records accurate remain important regardless of how much automation a lender uses. Building financial stability also involves practical steps such as creating an emergency fund, exploring extra income through mystery shopper jobs, or learning how to rent out your car.
Financial disclaimer:
This article is for general informational and educational purposes only and does not constitute personalized financial, legal, or lending advice. Credit-scoring methods and borrower protections vary by lender and jurisdiction. Consult the relevant financial institution or a qualified professional for guidance about a specific application.