AI Fraud Detection: A payment arrives that looks almost identical to hundreds of legitimate transactions processed every day. The amount seems normal, the merchant appears familiar, and the account has not raised any obvious alarms. Yet something about the transaction suggests that it may be fraudulent.
Identifying suspicious activity like this is one of the challenges artificial intelligence is helping financial institutions address. AI fraud detection systems analyze transaction patterns, account behavior, and other available signals to identify activity that deserves closer examination.
Banks, payment providers, online businesses, and financial technology companies can use these systems to improve fraud monitoring and prioritize investigations. However, AI cannot identify every scam or guarantee that every flagged transaction is fraudulent. Effective protection requires reliable data, appropriate security controls, and human oversight.
Key Takeaways
- AI fraud detection uses machine learning and other analytical techniques to identify suspicious activity.
- Financial institutions can use AI to monitor payments, detect unusual account behavior, and prioritize investigations.
- AI can identify patterns across large volumes of transactions, but false alerts and missed fraud remain possible.
- Fraud detection systems must balance security with customer privacy and convenient access to legitimate transactions.
- AI works best as part of a broader fraud prevention strategy rather than as a standalone solution.
What Is AI Fraud Detection?
AI fraud detection is the use of artificial intelligence to identify transactions, accounts, or activities that may indicate fraud.
Traditional fraud detection systems often rely on predefined rules. For example, a payment might be flagged if it exceeds a particular amount or occurs in a location associated with unusual account activity.
AI-based systems can analyze more complex relationships between data points. Machine learning models may learn from historical transactions and known fraud cases to estimate whether new activity resembles suspicious patterns.
A bank might consider transaction amount, timing, device information, payment history, and other permitted signals when evaluating a transfer.
The system may then assign a risk score, flag the activity, request additional authentication, or send the case to an investigation team.
A high risk score does not prove that fraud has occurred. It indicates that the activity may require additional checks.
How AI Fraud Detection Works
AI fraud detection typically involves several connected stages, from collecting relevant information to responding to suspicious activity.
1. Collecting Transaction Data
The system receives information about transactions and related activity. Depending on the application, this may include payment amounts, timestamps, merchant details, account history, device signals, and authentication results.
The quality of this information matters. Missing, inaccurate, or outdated data can reduce the reliability of the system.
Financial organizations must also ensure that data collection and use comply with applicable privacy and security requirements.
2. Establishing Normal Patterns
Machine learning models can analyze historical data to identify patterns associated with ordinary account behavior and known fraudulent activity.
For example, a system may learn that an account typically makes small purchases in a particular region and rarely sends large transfers.
A sudden behavior change may trigger additional scrutiny, particularly when several unusual signals appear together.
However, legitimate behavior changes too. A customer may travel, replace a device, or make an unusually large purchase. Models must account for this variability to avoid treating every deviation as suspicious.
3. Evaluating New Transactions
When a new transaction occurs, the system evaluates the available information against its rules, learned patterns, and risk thresholds.
A transaction may receive a low, medium, or high risk assessment, depending on the system’s design.
Some systems make assessments in milliseconds, allowing payment providers to evaluate risk before authorizing a transaction. Others analyze activity after the event to identify patterns that require investigation.
4. Triggering a Response
The response depends on the level of risk and the institution’s policies.
Possible actions include:
- Approving a transaction when risk appears low.
- Requesting additional authentication.
- Temporarily holding a transaction for review.
- Alerting a customer about unusual activity.
- Referring the case to a fraud investigation team.
The goal is to apply proportionate checks rather than automatically blocking every transaction that differs from historical behavior.
5. Learning From Confirmed Cases
Fraud teams may use investigation results and confirmed cases to improve detection systems.
Models can be retrained or recalibrated as criminal techniques change and new patterns emerge. However, updates need testing because changes that improve detection in one area may increase false alerts in another.
Ongoing monitoring is essential. A model that performed well in the past may become less effective when fraud patterns or customer behavior change.
Common Types of Fraud AI Can Help Detect
AI fraud detection is used across different financial activities. The methods and available signals vary by industry and transaction type.
Payment Card Fraud
AI systems can examine card transactions for unusual patterns, including unexpected spending behavior, suspicious merchant activity, or combinations of signals associated with stolen card details.
A flagged payment may trigger additional verification before it is approved.
Account Takeover
Account takeover occurs when someone gains unauthorized access to another person’s financial account.
AI systems can help identify unusual login behavior, unfamiliar device activity, unexpected account changes, or suspicious transfers following a login.
These signals are not conclusive on their own. Legitimate customers may change devices, travel, or use different networks.
Identity Fraud
Criminals may use stolen or fabricated personal information to open accounts or impersonate legitimate customers.
AI can support identity verification by analyzing permitted document information, checking for inconsistencies, and identifying patterns associated with suspicious applications.
Automated verification can make mistakes, especially when documents are unclear or a person’s circumstances do not match typical patterns. Additional review may be necessary.
Transaction and Payment Fraud
AI systems can help identify unusual transfers, suspicious payment sequences, or activity that resembles previously observed fraud.
For example, several rapid transfers following an unexpected account login may warrant further investigation.
The value comes from evaluating multiple signals rather than relying on one transaction characteristic alone.
Merchant and E-Commerce Fraud
Online businesses may use AI to assess suspicious orders, payment attempts, account registrations, and refund requests.
A system may consider purchase behavior, device signals, transaction history, and other permitted information when deciding whether an order needs additional verification.
Businesses must balance fraud prevention against the risk of incorrectly rejecting legitimate customers.
Money Laundering Indicators
Financial institutions may use machine learning and analytical tools to identify transaction patterns that warrant further investigation for possible money laundering.
AI can help connect activity across accounts or prioritize alerts for compliance teams.
However, unusual transactions are not proof of criminal activity. Investigators must examine relevant context and follow applicable legal and reporting procedures.
AI Fraud Detection vs. Traditional Fraud Detection
Traditional systems and AI models can complement each other. Many financial organizations use a combination rather than relying entirely on one approach.
| Feature | Traditional rule-based detection | AI-based detection |
| Main approach | Predefined rules and thresholds | Patterns learned from data, often combined with rules |
| Pattern recognition | Effective for known, clearly defined scenarios | Can identify more complex relationships in suitable data |
| Adaptability | Rules require manual or scheduled changes | Models may be retrained as patterns change |
| Explainability | Individual rules can be relatively easy to interpret | Some models are more difficult to explain |
| Data requirements | Can operate with relatively limited inputs | Performance may depend on substantial, relevant data |
| False alerts | Can occur when rules are too broad | Can occur when models misclassify legitimate behavior |
| Maintenance | Requires rule review and updates | Requires model monitoring, validation, and updates |
AI does not automatically outperform traditional systems in every situation. A clear rule may be more reliable for a simple, well-defined risk, while a machine-learning model may help when suspicious behavior involves multiple interacting signals.
A layered approach can combine established rules, AI-based risk assessments, authentication controls, and investigation procedures.
Benefits of AI Fraud Detection
Faster Identification of Suspicious Activity
Automated systems can evaluate transactions rapidly, helping organizations identify potentially fraudulent activity before it progresses further.
The speed advantage is particularly useful in payment environments where decisions must be made quickly.
Analysis of Large Volumes of Data
Financial institutions may process vast numbers of transactions across accounts, merchants, and payment channels.
AI can help analyze patterns across this information more efficiently than manual review alone.
Identification of Complex Patterns
Fraud does not always appear as a single unusually large payment. It may involve a sequence of small transactions, related accounts, or changes in behavior over time.
Machine learning can help identify relationships that simpler rules may overlook.
More Focused Investigations
By assigning risk scores and grouping related alerts, AI can help fraud teams prioritize cases that require attention.
This can make better use of investigative resources, provided that the model is properly calibrated and important cases are not overlooked.
Adaptation to Changing Threats
Fraud patterns change as criminals develop new methods. Models can be updated using new evidence and tested against emerging threats.
However, adaptation is not automatic in every system. Organizations need monitoring, quality data, and a controlled process for deploying updates.
Limitations and Risks of AI Fraud Detection
False Positives
A false positive occurs when a legitimate transaction is incorrectly flagged as suspicious.
This can delay payments, block purchases, or require customers to complete additional verification.
For example, a person buying a high-value item while traveling may trigger a system designed to identify unusual spending.
Organizations must measure both fraud detection and customer inconvenience when evaluating system performance.
False Negatives
A false negative occurs when fraudulent activity is not identified.
Criminals may deliberately imitate legitimate behavior, use compromised accounts with established histories, or change tactics to avoid detection.
No model can guarantee that every fraudulent transaction will be recognized.
Biased or Incomplete Data
If training data does not adequately represent the people, transactions, and situations the system encounters, its results may be less reliable for certain customers or circumstances.
Financial institutions should test system performance across relevant populations and transaction types while respecting privacy and legal requirements.
Privacy Concerns
Fraud detection may involve sensitive information about customer behavior, devices, locations, and transactions.
Organizations need appropriate controls over which information is collected, who can access it, how long it is retained, and how it is used. These safeguards are important across financial activities, from earning extra income through mystery shopper jobs to exploring ways to rent out your car or building an emergency fund.
More data does not automatically produce better or more responsible detection.
Evolving Criminal Techniques
Fraudsters can change their methods to exploit weaknesses in detection systems. They may also use AI to create convincing impersonation attempts, fake documents, or targeted phishing messages.
Fraud prevention therefore requires a combination of technical monitoring, secure authentication, employee training, and customer awareness.
Operational Complexity
AI systems require testing, monitoring, maintenance, and knowledgeable staff. Poorly managed models may become less accurate or create excessive alerts.
Organizations must also consider integration costs, system reliability, and procedures for handling situations the model cannot confidently assess.
How Businesses Can Implement AI Fraud Detection
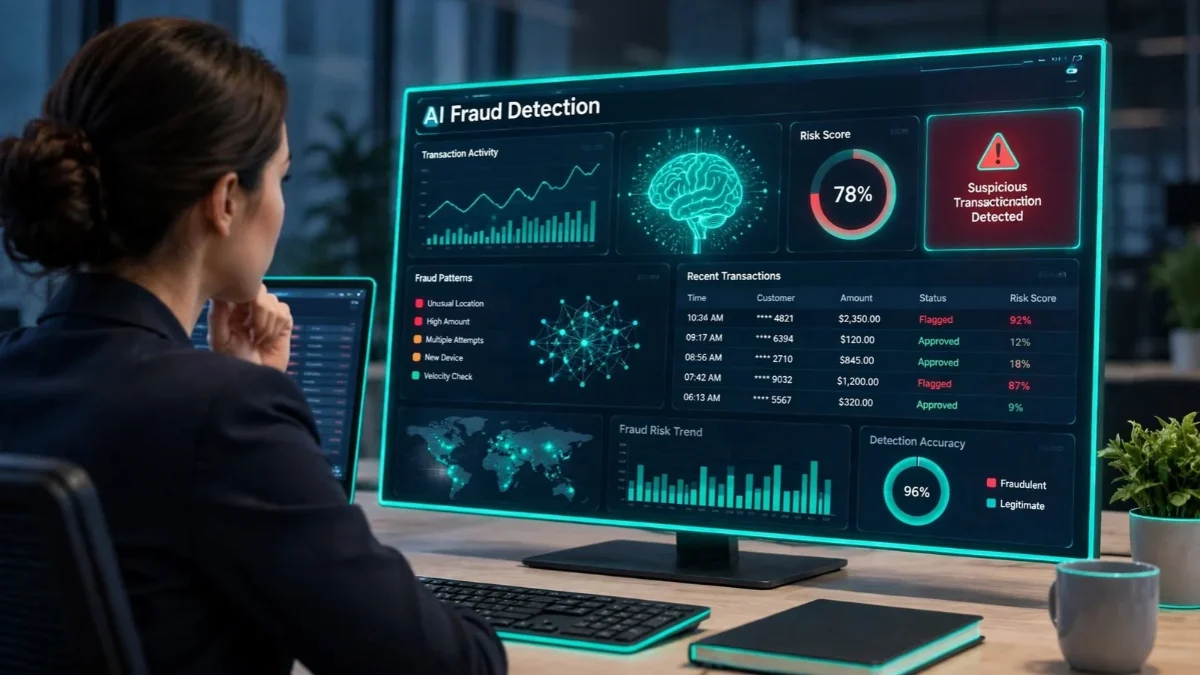
An organization considering AI fraud detection should start with a clearly defined problem rather than selecting a model simply because it uses advanced technology.
Step 1: Identify the Fraud Problem
Determine whether the priority is payment fraud, account takeover, suspicious applications, refund abuse, or another specific risk.
Different problems require different data, detection methods, and response procedures.
Step 2: Assess Available Data
Review whether the organization has reliable, relevant, and legally usable data for the intended purpose.
Identify missing information, inconsistent records, and potential sources of bias before building or purchasing a system.
Step 3: Choose an Appropriate Approach
Depending on the problem, a business may use rule-based controls, supervised machine learning, anomaly detection, or a combination of methods.
A simpler system may be sufficient when the risk is well understood and the rules are effective.
Step 4: Test Before Deployment
Evaluate the system using historical cases and appropriate testing scenarios. Measure how often it identifies fraud, how many legitimate transactions it incorrectly flags, and how well it performs under different conditions.
Testing should also examine the consequences of incorrect decisions.
Step 5: Define Response Procedures
Decide what happens when the system flags activity. Establish thresholds for additional authentication, manual review, temporary restrictions, and escalation.
High-impact decisions should have suitable oversight and correction procedures.
Step 6: Monitor Performance
Track fraud losses, false alerts, customer complaints, investigation outcomes, and changes in transaction patterns.
Review the system regularly and update it when evidence shows that its performance or assumptions have changed.
How Consumers Can Protect Themselves
AI fraud detection can provide an additional layer of protection, but individuals should not rely entirely on banks or payment providers to prevent fraud.
Use these practical safeguards:
- Enable multifactor authentication wherever available.
- Use unique passwords for banking and financial accounts.
- Turn on transaction notifications and review account activity.
- Verify payment requests through a trusted, independent communication channel.
- Never share one-time authentication codes or banking credentials with unsolicited callers or messages.
- Be cautious of urgent requests to transfer money to a supposedly safe account.
- Keep devices and financial applications updated.
- Contact your bank promptly through its official channels if you notice an unauthorized transaction.
Remember that scammers may imitate bank employees or use convincing messages and voice recordings. An alert from a familiar-looking account does not prove that the communication is legitimate.
How to Measure AI Fraud Detection Performance
A fraud detection system should be assessed using several measures rather than a single accuracy score.
| Measure | What it indicates | Why it matters |
| Detection rate | The proportion of relevant fraud cases identified | Helps assess how much fraud the system catches |
| False-positive rate | How often legitimate activity is incorrectly flagged | Indicates potential customer inconvenience |
| False-negative rate | How often fraudulent activity is missed | Helps assess remaining exposure |
| Investigation workload | The volume of alerts requiring human review | Shows whether the system is manageable operationally |
| Financial losses | Losses associated with fraudulent activity | Connects detection performance to business impact |
| Response time | How quickly suspicious activity is assessed | Matters when intervention can prevent additional loss |
Metrics must be interpreted in context. For example, a model may achieve a high overall accuracy score simply because fraudulent transactions are rare. Measuring how well it identifies actual fraud and how often it flags legitimate activity provides a more useful picture.
Frequently Asked Questions
What is AI fraud detection?
AI fraud detection uses artificial intelligence and data analysis to identify transactions, accounts, or activities that may indicate fraud. It can help financial institutions prioritize alerts and investigate suspicious behavior.
How does machine learning detect fraud?
Machine learning models analyze historical information to identify patterns associated with legitimate and fraudulent activity. They then evaluate new activity for similarities or unusual characteristics. Their reliability depends on data quality, model design, and ongoing monitoring.
Can AI stop all financial fraud?
No. AI can help identify suspicious behavior, but it can miss fraud or flag legitimate transactions incorrectly. Effective prevention requires additional controls, investigation procedures, secure authentication, and customer awareness.
Is AI fraud detection used by banks?
Banks and other financial institutions use automated analytics and, in many cases, AI or machine-learning systems for fraud monitoring and risk assessment. The specific technologies and capabilities vary by institution.
What is the difference between AI fraud detection and fraud prevention?
Fraud detection focuses on identifying activity that may be fraudulent. Fraud prevention includes the broader measures used to reduce opportunities for fraud, such as authentication, transaction limits, account security, customer education, and detection systems.
Can small businesses use AI fraud detection?
Yes. Depending on their needs, small businesses can use payment providers and financial software that incorporate automated fraud screening. They should review the available controls, costs, false-decline policies, and responsibilities for handling disputed transactions.
Does AI fraud detection invade privacy?
It can raise privacy concerns when systems collect or analyze sensitive information without appropriate limits or transparency. Responsible implementation requires lawful data use, access controls, data minimization, and suitable retention policies.
Final Thoughts
AI fraud detection helps financial institutions and businesses identify suspicious transactions, analyze complex patterns, and prioritize investigations. It can improve the speed and scale of fraud monitoring, but it cannot eliminate financial crime or replace every human decision.
The most effective systems combine AI with reliable data, traditional security controls, ongoing testing, and clear procedures for handling uncertain cases. Consumers also play an important role by protecting their accounts, verifying payment requests, and responding quickly to suspicious activity.
AI is a valuable tool in the fight against financial fraud, but responsible implementation and consistent security practices remain essential.
Financial disclaimer:
This article is for general informational and educational purposes only and does not constitute financial, legal, or cybersecurity advice tailored to your circumstances. Fraud detection capabilities vary by provider, and no system can guarantee complete protection against financial loss.