Financial planning platforms for freelancers should help you connect three things: what your business earns, what your household needs, and what you want your money to achieve later. Those numbers often live in different places. Invoices sit in one tool, expenses appear in your bank account, and your retirement plan is a promise to deal with it when work becomes less hectic.
Then a client pays late, your laptop needs replacing, and the distance between a busy business and a comfortable personal life becomes obvious. A useful platform helps close that distance. The right choice depends on whether you need clearer business records, a stronger spending plan, or a way to model your financial future.
Editorial note: Product information was reviewed in November 2026. This is a research-based comparison rather than a hands-on ranking. Features, plan limits, and country availability can change.
Key Takeaways
- Business accounting, household budgeting, and long-term planning serve different purposes.
- An unpaid invoice is different from cash available to spend.
- Compare platforms by the decisions they help you make.
- Confirm local bank support, currency handling, and relevant tax assumptions.
- You may need a small combination of tools rather than one large subscription.
- Review costs after introductory offers expire.
What Counts as a Financial Planning Platform for Freelancers?
For this guide, the term includes three kinds of software: tools for planning personal spending, tools for understanding business finances, and tools for modeling longer-term goals. An accounting platform can tell you who owes money. A budgeting platform can help allocate money received. A scenario planner can examine what different saving and spending assumptions might mean over time.
These capabilities complement one another, but they are not interchangeable. The list below identifies each platform’s role so you can build a useful system without paying for overlapping dashboards.
Which Platforms Should You Compare?
| Platform | Main role | Useful freelancer question |
| YNAB | Available-money budgeting | What must this payment cover? |
| PocketSmith | Personal cash-flow forecasting | What happens if a client pays late? |
| Monarch | Household financial coordination | How does freelance income support our shared plan? |
| Quicken Simplifi | Spending and financial tracking | What remains after planned commitments? |
| Lunch Money | Multi-currency tracking | How much did overseas earnings become locally? |
| Tiller | Spreadsheet-based tracking | Can I build reports around my workflow? |
| Fina | Flexible budgets and reporting | Can I organize money around my own planning periods? |
| ProjectionLab | Long-term financial modeling | How might a different workload affect my future? |
| Boldin | Retirement-focused planning | What assumptions drive my retirement plan? |
| Empower Personal Dashboard | Overall financial visibility | How do my assets and debts fit together? |
| FreshBooks | Freelance business administration | What have I billed, collected, and spent? |
| QuickBooks Solopreneur | Solo-business records | Are income and expenses organized? |
| Wave | Small-business bookkeeping | What do the business records reveal? |
| Zoho Books | Business accounting and reporting | How do receivables, expenses, and cash flow connect? |
| Goodbudget | Envelope budgeting | Which money belongs to future commitments? |
The order reflects different uses, rather than a ranking of overall quality.
1. YNAB: Turn Client Payments Into a Personal Plan
YNAB centers on assigning available money to priorities. It offers targets, manual transaction entry, and bank imports where supported. That approach can suit freelancers who receive payments in uneven amounts. A $2,000 deposit may need to support household expenses over several weeks. Allocating it makes those commitments visible before discretionary spending grows.
The platform supports the budgeting process, but it does not determine how much you owe in business expenses or taxes. Establish what belongs in your personal plan first.
Trial task: Allocate money already received without including outstanding invoices. Check whether you can see which essential expenses are covered.
2. PocketSmith: Examine the Timing of Money
PocketSmith emphasizes budgeting and cash-flow forecasting, including calendar-based planning. It is relevant when your monthly totals look reasonable but individual weeks remain uncomfortable. For example, a software renewal may fall before a large client payment. A forecast gives you a way to examine that sequence and test a delay.
The output depends on your assumptions. Treat it as a scenario you can adjust rather than a promise about future balances.
Trial task: Move an expected payment back by two weeks and observe the effect on upcoming commitments.
3. Monarch: Connect Freelance Earnings With Household Goals
Monarch brings together account information, budgets, goals, transaction categorization, and net-worth tracking. It also supports collaboration. That can help when freelance earnings support a household alongside another person’s salary.You can develop a common picture of spending and goals instead of each person interpreting a bank balance differently.
Agree on the household contribution from freelance work and how additional income will be handled. Shared information becomes more useful when it supports a shared decision.
Trial task: Review a lower-income month together and confirm that both people understand the plan.
4. Quicken Simplifi: Keep Everyday Finances Organized
Quicken Simplifi offers spending plans, savings tools, reporting, and projected cash flow. Consider it if you want an organized personal overview and a way to revisit spending as income changes. The important distinction is between an expected payment and a confirmed deposit. Keep your assumptions conservative enough that a delay does not make the whole plan unusable.
Simplifi and Quicken Classic are separate products, so check the precise subscription and features you are comparing.
Trial task: Reduce expected income and assess how easily you can revise spending priorities.
5. Lunch Money: Follow Income Across Currencies
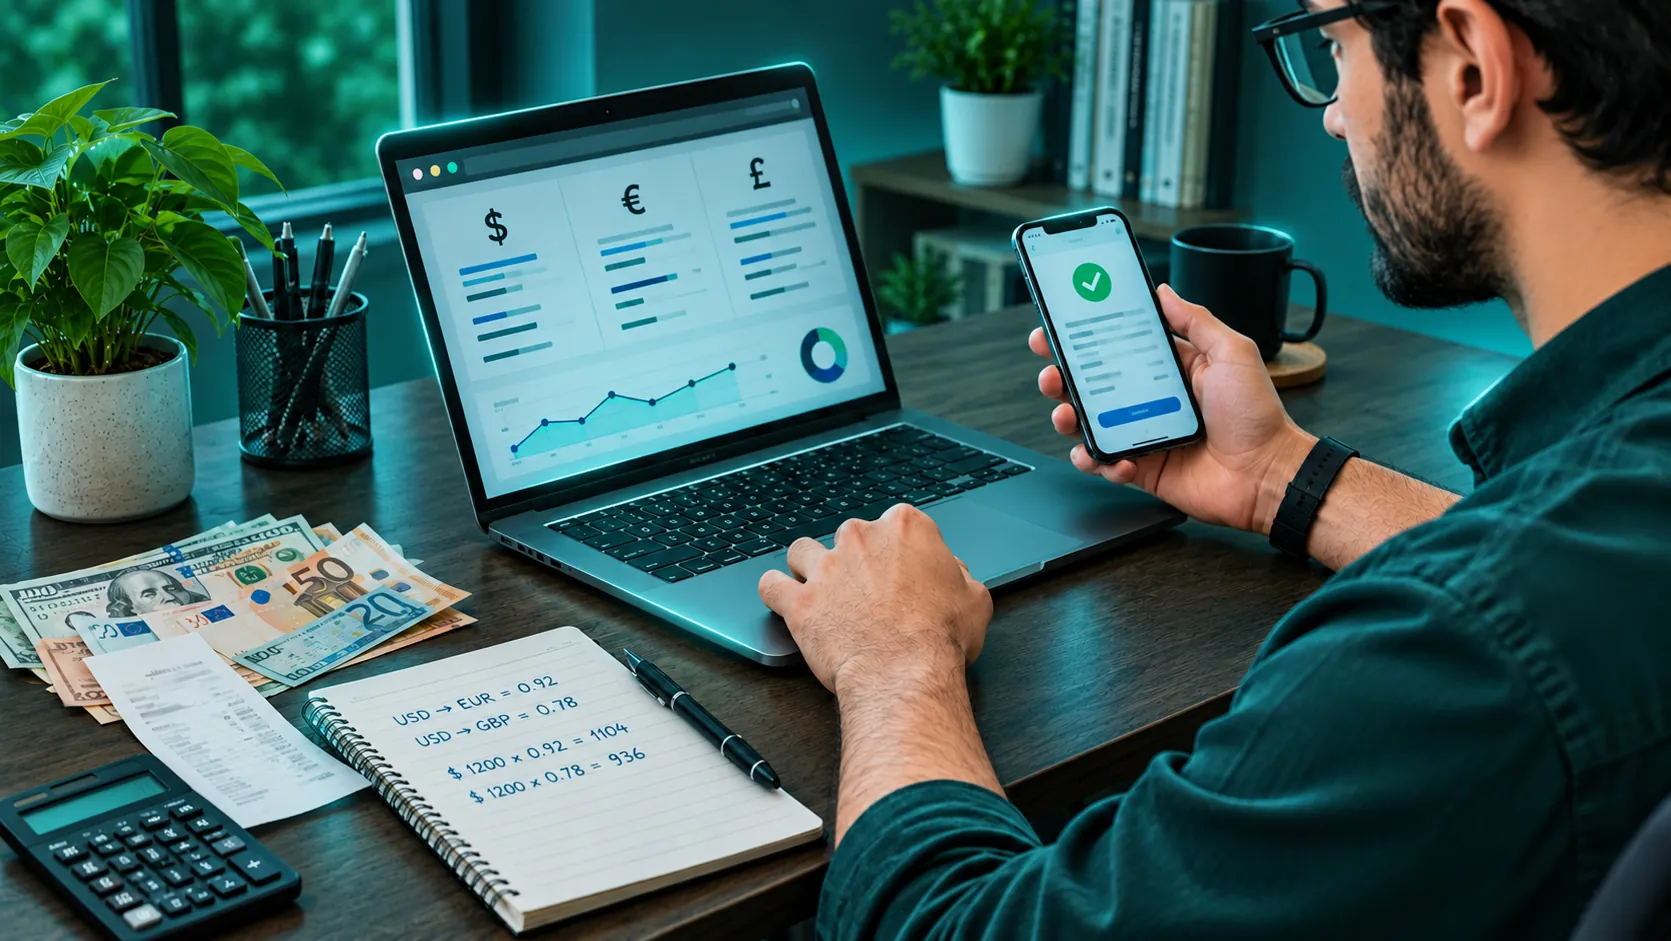
Lunch Money supports multi-currency tracking and reporting in a selected primary currency. Its documentation describes historical exchange rates for transactions. That is relevant to freelancers working with international clients. The invoice value, payment-platform balance, and final local deposit may differ. Fees and conversion rates can change how much becomes available.
A consistent reporting view helps organize the picture, but you still need to reconcile actual receipts.
Trial task: Follow one overseas payment through fees, conversion, and transfer. Make sure transfers between your own accounts do not appear as additional income.
6. Tiller: Build Around Your Spreadsheet Workflow
Tiller brings financial transactions and balances into Google Sheets or Microsoft Excel. Its documentation includes workflows for personal finances and small businesses, recommending separate spreadsheets when tracking both purposes. Tiller currently supports US customers. It may appeal if you already understand spreadsheets and want more control over categories, calculations, and reports.
That flexibility also creates responsibility. A formula error can distort a useful-looking dashboard, so reconcile results against original records.
Trial task: Create a simple income-and-expense view and verify its totals before adding custom calculations.
7. Fina: Organize Budgets Around Your Own Periods
Fina describes flexible budgeting and financial planning with multiple budgets and user-defined time ranges. That makes it worth examining if a conventional calendar-month structure does not fit how you prefer to review finances. You might want to assess a particular period of work or organize different financial views. Confirm during the trial that the exact workflow you have in mind is supported.
Flexibility should make the important numbers easier to understand. Avoid building so many views that maintaining them becomes another job.
Trial task: Set up one planning period relevant to your work and check whether the reports answer a specific question.
8. ProjectionLab: Model Life Beyond the Next Invoice
ProjectionLab is a financial modeling platform for examining longer-term scenarios. Its documented capabilities include cash-flow projections and additional planning features depending on the subscription. It belongs in a different category from daily expense tracking. A freelancer might use scenario planning to explore the effect of reducing working hours, changing spending, or saving different amounts over time.
These are conditional projections. Growth rates, inflation, taxes, and income assumptions influence the results.
Trial task: Compare two workload-and-saving scenarios. Check country and tax-model suitability before relying on detailed outputs.
9. Boldin: Give Retirement Planning Its Own Space
Boldin focuses on retirement planning, bringing income, expenses, assets, and other assumptions into a longer-term model. Its planner is based on US tax law and US retirement structures, which is a significant limitation for readers elsewhere. For a US-based freelancer, it may help organize questions that regular spending tools leave unanswered.
You can examine how assumptions interact rather than treating retirement as one distant savings target. Feature depth depends on the plan.
Trial task: Change a retirement date or spending assumption and identify what drives the result. Readers outside the US should assess suitability carefully.
10. Empower Personal Dashboard: See the Wider Financial Position
Empower offers a free Personal Dashboard and financial tools for supported accounts, including investments, borrowing, savings, and retirement accounts. It may help if your financial information is spread across institutions and you want an overall view. That view can connect current work with accumulated assets and outstanding debts. However, it does not replace the process of deciding how to allocate the next payment.
Check regional eligibility and account connectivity. Review any separate advisory offering on its own terms.
Trial task: Connect supported accounts and ask whether the dashboard reveals anything actionable that your existing records do not.
11. FreshBooks: Understand the Business Behind Your Income
FreshBooks offers invoicing, expense tracking, billable time tracking, payment acceptance, and reporting for freelancers. Its role in financial planning begins with understanding your business activity. A full calendar does not automatically produce healthy personal finances. You need to know what was billed, what was paid, and what costs were incurred.
Reporting capabilities, client limits, and additional features vary by plan. Compare the subscription required for your actual workload.
Trial task: Trace one project from its invoice through payment and related expenses. Check whether you can distinguish work completed from cash collected.
12. QuickBooks Solopreneur: Organize Solo-Business Records
QuickBooks markets its Solopreneur offering toward single-owner, self-employed businesses, with capabilities for organizing income and expenses and supporting related administrative tasks. Plan features and product naming deserve close attention. The current offering includes different subscription levels, and tax-oriented features reflect the relevant market.
Its planning value comes from cleaner business records. Those records can inform what the business costs and how performance changes. Do not assume a tax feature designed for US reporting applies to your location.
Trial task: Review categorization and reporting with representative transactions. Confirm country suitability and any accountant-access requirements before choosing a plan.
13. Wave: Review Business Performance in Supported Markets
Wave provides small-business accounting tools and reports, with automation features available through its paid offering. It is available for businesses located in the United States and Canada, making eligibility an early check. For an eligible freelancer, business records can reveal income, expenses, and cash-flow trends that are difficult to see from a bank balance alone.
Remember that profit and available cash can differ. Read report dates and accounting settings carefully when drawing conclusions.
Trial task: Reconcile a month and compare its reports with actual payments received and expenses paid.
14. Zoho Books: Connect Receivables and Business Reporting
Zoho Books offers accounting and financial reporting, including views of receivables, payables, income, expenses, and cash flow. It can be worth comparing when freelance operations require more structure. Perhaps you have numerous invoices, recurring business costs, or project records that are becoming difficult to manage manually.
Choose the edition appropriate to your country and confirm plan limits. Features documented for one regional edition should not be assumed to apply everywhere.
Trial task: Review outstanding invoices alongside upcoming bills and identify the information you need for your next cash decision.
15. Goodbudget: Protect Money for Future Commitments
Goodbudget uses digital envelopes to divide money among purposes. Its free plan has account and envelope limits, while Premium expands capacity and includes US bank syncing. The method can support a freelancer’s personal finances by distinguishing current spending money from money reserved for later.
An annual bill or a quieter work period feels less surprising when it already has an allocation. Goodbudget serves this budgeting role; it is not a substitute for business bookkeeping or a retirement model.
Trial task: Create envelopes for essentials, an annual expense, and an income gap. Check whether the process remains manageable.
How Can You Connect Business Income With Personal Goals?
Use a three-stage review: collected, committed, available. Collected means money actually received. Committed means amounts needed for business costs, relevant reserves, and other obligations. Available means what remains for an allocation decision.
Consider this hypothetical monthly example:
| Review step | Amount |
| Client payments collected | $5,000 |
| Business costs and commitments | −$1,000 |
| Illustrative tax reserve | −$900 |
| Business contingency allocation | −$300 |
| Remaining for a personal allocation decision | $2,800 |
The reserve is an example, not a recommended tax rate. Your legal structure and local requirements also affect how business money can be transferred or paid to you. The practical point is that $5,000 collected is different from $5,000 available for household spending. Accounting tools help establish business records. Budgeting tools help assign personal money. Long-term models help explore what consistent allocations might support.
What Should You Check Before Subscribing?
- The platform serves your country and circumstances.
- Your banks and currencies are supported, or imports are practical.
- Tax assumptions match the relevant jurisdiction.
- You understand which features require higher plans.
- Reports distinguish transfers, income, and expenses correctly.
- You can export records and share appropriate access.
- Renewal costs remain reasonable after promotions.
- The tool answers a question your existing system cannot.
Start with the weakest part of your current process. Add another platform only when it fills a clear gap.
Frequently Asked Questions
Do freelancers need more than one financial platform?
Sometimes. Business records, personal budgeting, and long-term modeling are different jobs. Use the smallest combination that covers your actual needs.
Is accounting software the same as financial planning software?
No. Accounting organizes business records. Financial planning uses information and assumptions to guide future decisions. Some tools overlap, but the scope differs.
Can these platforms calculate my taxes?
Some offer tax-related features for particular markets. Confirm the jurisdiction, supported circumstances, and limitations before relying on any estimate.
Which option suits freelancers in Pakistan?
Check local eligibility, bank support, currencies, and tax assumptions individually. US-focused retirement or tax software may be unsuitable, even if you can access its website.
How often should I review my financial plan?
A regular cash review and a broader periodic review serve different purposes. Revisit assumptions when income, household commitments, or major goals change.
Make Your Work Support the Life You Want
A freelancer’s financial plan should connect the effort of earning money with something beyond the next invoice. Start by understanding the business. Establish what is available personally, give that money clear priorities, and examine longer-term goals with realistic assumptions. The most useful platform is the one that helps you make the next decision with a clearer view of its consequences.