Auto Insurance: Buying car insurance isn’t something most people get excited about. You need it to protect yourself financially and meet your state’s legal requirements. But when you start looking at different companies and policies the choices can get confusing pretty quickly.
One company may offer a lower monthly payment while another provides better accident coverage or a smoother claims process. And sometimes the cheapest quote isn’t the one that saves you the most money in the long run.
So how do you find the best auto insurance without paying for coverage you don’t really need?
The answer is to look beyond the price. You should understand what each policy covers and how the insurance company treats its customers when something goes wrong. A little research before signing up can save you from an expensive surprise later.
This guide from Weird Wealth explains how auto insurance works and what to check before choosing a provider. We’ll also look at some well-known companies and practical ways to find coverage that fits your budget.
Key Takeaways
-
The best auto insurance depends on your location and driving history as well as your vehicle and coverage needs.
-
Comparing quotes from several insurers is one of the easiest ways to find a competitive price.
-
Liability insurance covers damage or injuries you cause to others.
-
Collision and comprehensive coverage protect your own vehicle in different situations.
-
Customer complaints and claims service deserve attention alongside monthly premiums.
-
Discounts and higher deductibles may help reduce insurance costs.
-
The cheapest policy isn’t always the best choice if it leaves you with too little protection.
What Is the Best Auto Insurance?
The best auto insurance is a policy that gives you suitable financial protection at a price you can comfortably afford. It should also come from a company with reliable customer service and the financial ability to handle covered claims.
There isn’t one insurance provider that works best for every driver. Someone with a new car may need different coverage from someone driving an older vehicle. A young driver may also receive very different quotes from an experienced driver.
For this reason it’s better to compare insurance companies based on your own circumstances rather than choosing a company simply because it appears at the top of a ranking.
Recent insurance comparisons have highlighted companies such as Amica and GEICO for their overall offerings. Travelers has also received attention for affordability while Progressive stands out for its optional coverage features. These are useful starting points but their prices and availability vary by state and driver.
Which Auto Insurance Companies Are Worth Comparing?
When looking for the best car insurance companies start with established providers that offer coverage in your state. Then compare their prices and policy details.
Here are several companies worth researching.
1. Amica
Amica is worth considering if customer experience and coverage options matter to you. NerdWallet named it its best overall car insurance company in its October 2026 analysis.
However this doesn’t mean it will offer the lowest price in every state. Get a personal quote before making a decision.
2. GEICO
GEICO is a popular option for drivers who want to explore different discounts and manage their policies online.
Its discount options can make it worth comparing for drivers who qualify. Still check the actual coverage limits and deductible instead of focusing only on the advertised price.
3. Travelers
Travelers is another provider to include when comparing affordable auto insurance.
NerdWallet highlighted Travelers for affordability in its October 2026 review. Your own quote may be different depending on your driving record and location.
4. Progressive
Progressive offers several optional coverage features that may appeal to drivers who want more flexibility.
It’s worth checking if its available add-ons match your needs. Remember that additional coverage can increase the premium.
5. Acuity
Acuity is another company worth researching. NerdWallet highlighted its comparatively low complaint levels in its October 2026 analysis.
Availability is not the same everywhere so check whether it operates in your state before requesting a quote.
A quick reminder: These companies are research starting points rather than a guaranteed ranking for every driver. Their rates and services can change.
What Types of Auto Insurance Coverage Do You Need?
Before choosing an insurance company you should understand what you’re actually buying. Two policies can have similar monthly prices but provide very different protection.
Here are the main types of car insurance coverage.
Liability Coverage
Liability insurance helps pay for injuries or property damage you cause to another person in an accident where you’re legally responsible.
It generally includes:
-
Bodily injury liability: Helps cover medical expenses and related costs for people injured in an accident you cause.
-
Property damage liability: Helps pay for damage to another person’s vehicle or property.
Most US states require drivers to carry minimum liability coverage. However state minimums may not provide enough protection after a serious accident.
Collision Coverage
Collision insurance helps pay to repair or replace your own vehicle after an accident involving another vehicle or an object. It can apply even when you hit something like a fence or a wall.
This coverage is particularly worth considering if you own a newer vehicle or couldn’t comfortably afford major repairs yourself.
Comprehensive Coverage
Comprehensive insurance covers certain types of damage that don’t involve a collision. Depending on your policy this can include:
-
Vehicle theft
-
Fire damage
-
Falling objects
-
Hail and certain weather damage
-
Vandalism
-
Animal-related damage
Collision and comprehensive coverage usually have separate deductibles. If your car is financed or leased the lender may require both.
Uninsured and Underinsured Motorist Coverage
Not every driver carries enough insurance. Some have no coverage at all.
Uninsured and underinsured motorist coverage can help protect you if you’re injured by a driver who has no insurance or insufficient insurance. Availability and requirements depend on your state.
Personal Injury Protection
Personal injury protection or PIP helps cover certain medical expenses and other costs after an accident. Depending on the state and policy it may also cover lost wages.
It’s especially relevant in states where PIP is required or forms part of a no-fault insurance system.
What Factors Affect Auto Insurance Rates?
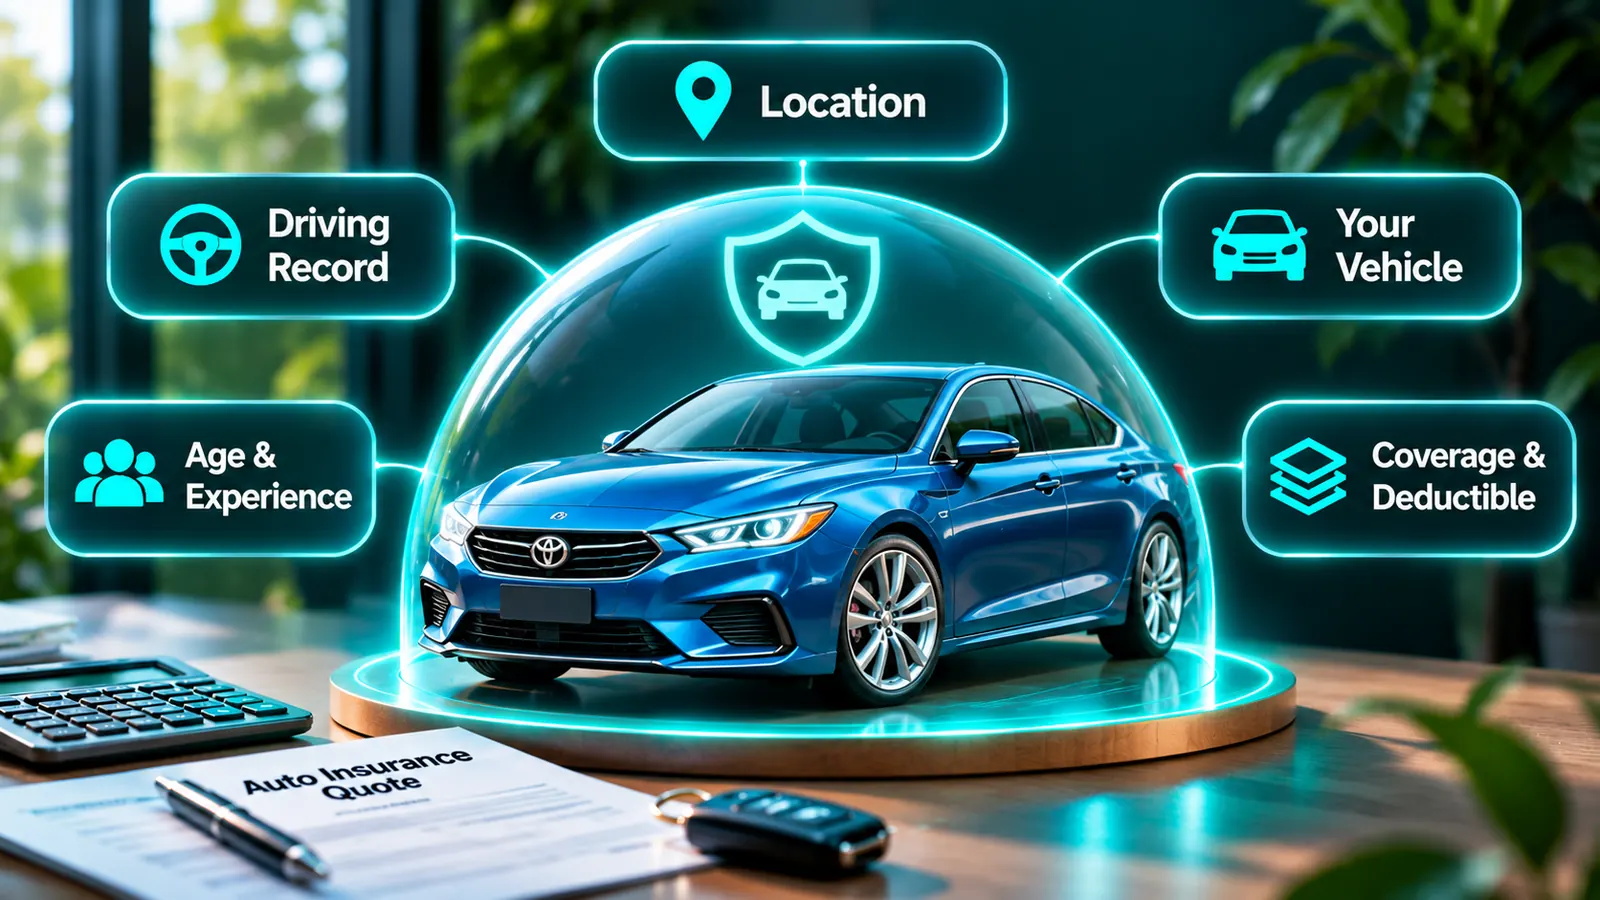
Have you ever wondered why two people driving similar cars receive completely different insurance quotes?
That’s because insurance companies assess risk using several factors. They estimate how likely a driver is to make a claim and how expensive that claim could become.
Some common factors include:
Your Driving Record
Your driving history can make a noticeable difference to your premium. Accidents and serious traffic violations may increase your rates. Drivers with a history of safe driving may qualify for better prices or safe-driver discounts.
Your Location
Where you live and park your car can affect your insurance costs. Insurers may consider local accident rates and vehicle theft as well as weather-related risks and repair costs.
Your Vehicle
A vehicle that’s expensive to repair or frequently targeted by thieves may cost more to insure. Safety equipment and anti-theft features can sometimes help reduce premiums.
Your Age and Driving Experience
Younger and less experienced drivers often face higher premiums because insurers consider them a higher risk.
Rates can change as drivers gain experience and maintain a good driving record.
Your Coverage and Deductible
Higher coverage limits usually cost more. A higher deductible can reduce your premium but it also means you’ll pay more yourself when making a covered claim.
Credit-based insurance scores may also be used where permitted by state law. The rules vary across the country.
How Can You Find Affordable Auto Insurance?
Finding affordable car insurance doesn’t mean choosing the smallest number on your screen. It means getting the protection you need without paying for unnecessary extras.
Here are some practical steps worth following.
1. Compare Quotes From Different Companies
Start by requesting quotes from at least three insurance providers. You can use online comparison services or visit insurers directly.
Make sure you’re comparing similar coverage limits and deductibles. Otherwise a cheaper quote might simply offer less protection.
The National Association of Insurance Commissioners (NAIC) also recommends comparing similar policies because prices can vary between insurers.
2. Ask About Available Discounts
Many insurers offer discounts that can lower your premium.
Depending on the company you may qualify for:
-
Safe-driver discounts
-
Multi-car discounts
-
Bundling discounts
-
Good student discounts
-
Anti-theft device discounts
-
Defensive driving course discounts
-
Low-mileage discounts
Don’t assume every discount is automatically applied. Ask the insurer which ones you qualify for.
3. Consider a Higher Deductible
A deductible is the amount you pay out of pocket before your insurance covers an eligible claim.
For example if your collision deductible is $1,000 you’ll generally pay the first $1,000 of covered repair costs.
Choosing a higher deductible may reduce your monthly premium. But make sure you can afford that amount if an accident happens.
4. Review Your Coverage Every Year
Your insurance needs can change over time. Perhaps you’ve paid off your vehicle or started driving fewer miles.
Review your policy when it renews. Check whether your coverage still makes sense and whether another provider can offer a better deal.
5. Check the Company’s Complaint History
A low premium doesn’t tell you everything about an insurance company.
Look at its customer complaints and financial information before purchasing a policy. The NAIC’s Consumer Insurance Search allows people to research insurance companies using complaint and financial information.
How Do You Choose the Right Auto Insurance Policy?
Once you’ve collected a few quotes take some time to review the actual policy details.
Here is a simple checklist:
-
Confirm that the insurance company is licensed in your state.
-
Check the liability limits and available coverage options.
-
Understand the collision and comprehensive deductibles.
-
Review exclusions and restrictions.
-
Ask how accident claims are handled.
-
Check available discounts and additional fees.
-
Make sure the policy fits your vehicle and financial situation.
Don’t feel pressured to purchase a policy during your first phone call or website visit. Take time to read the documents, compare your options, and ask questions if something isn’t clear.
The California Department of Insurance also recommends getting several written quotes and checking an insurer’s claims and customer service record before buying. As you review your finances, you may also find it helpful to explore ways to manage everyday expenses, such as choosing the right Best Buy credit card payment option, finding the best household budgeting apps, or comparing the best banks for checking accounts.
Why the Cheapest Auto Insurance Isn’t Always the Best
Imagine finding a policy that costs $40 less each month than another option. It sounds like an easy decision until you discover that the cheaper policy has much lower liability limits and a higher deductible.
If you cause a serious accident you could end up paying a significant amount yourself.
That’s why the best auto insurance should balance three things:
-
Price: Can you comfortably afford the premium?
-
Protection: Does the policy provide enough coverage for your needs?
-
Service: Can you trust the company to handle claims fairly and efficiently?
A policy should protect your finances rather than simply look attractive on a quote page.
Final Thoughts
Finding the best auto insurance takes a little more work than picking the first company that offers a low monthly payment. You need to understand your coverage and compare what different insurers actually provide.
Start with a few established providers and request quotes using the same coverage details. Check their customer complaints and available discounts. Then choose a policy that offers suitable protection without stretching your budget.
At Weird Wealth we believe good financial decisions start with understanding where your money goes. Car insurance is one of those regular expenses where a little research can make a real difference.
The right policy isn’t necessarily the cheapest one. It’s the one that helps protect you when you need it most.
Frequently Asked Questions
1. Which company offers the best auto insurance in 2026?
Companies worth comparing include Amica, GEICO, Travelers, Progressive and Acuity. Their prices and coverage vary by state so request personal quotes before choosing.
2. How can I get cheap car insurance?
Compare quotes from several providers and ask about discounts. Maintaining a clean driving record and choosing a deductible you can afford may also help reduce your premium.
3. Is full coverage auto insurance worth it?
Full coverage usually refers to a combination of liability, collision and comprehensive insurance. It can be useful if you have a newer or financed vehicle. However the right choice depends on your car’s value and financial situation.
4. What information do I need to get an auto insurance quote?
You will generally need your vehicle information and driving history along with your address and details about the drivers who will use the car. The insurer may also ask about your desired coverage and annual mileage.
5. Can I switch auto insurance companies anytime?
In many cases you can switch before your current policy expires. Check cancellation terms and possible fees first. Make sure your new coverage starts before your existing policy ends to avoid an insurance gap.
Disclaimer
This article is for informational and educational purposes only. Insurance coverage requirements and pricing vary by state and individual circumstances. Company examples are not personal recommendations or guarantees of affordability. Always review the full policy documents and consult a licensed insurance professional when necessary.