Imagine buying Bitcoin, swapping part of it for Ethereum, earning rewards from staking, and later selling some of your holdings to pay a bill. Your exchange account might show a single balance, but from a tax perspective, those actions can represent several different transactions.
That is why understanding crypto taxes matters even if you rarely trade. Buying and holding cryptocurrency may be treated differently from selling it, exchanging one token for another, earning staking rewards, or receiving tokens through an airdrop. The exact rules depend on where you live and the tax laws that apply to you.
The safest approach is to keep accurate transaction records throughout the year rather than trying to reconstruct everything when a tax deadline arrives.
Key Takeaways
- Crypto tax rules differ by country, and the same transaction can receive different treatment in different jurisdictions.
- Selling cryptocurrency for cash may create a taxable gain or loss.
- Swapping one cryptocurrency for another can have tax consequences even when no traditional currency is involved.
- Staking rewards, mining income, airdrops, and payments received in crypto may require separate consideration.
- Accurate records of transaction dates, values, fees, and cost basis make reporting easier.
What Are Crypto Taxes?
Crypto taxes are taxes that may apply to activities involving cryptocurrencies and other digital assets. Depending on local law, these activities can include selling coins, exchanging tokens, earning rewards, mining, receiving cryptocurrency as payment, or disposing of digital assets in other ways.
Tax authorities do not necessarily treat every crypto transaction the same way. Some activities may be classified as capital transactions, while others may be treated as income or fall under a different category.
Two concepts are especially important:
Capital gain or loss: The difference between the relevant proceeds from disposing of an asset and its adjusted cost basis, calculated under the applicable tax rules.
Crypto-related income: Cryptocurrency received through activities such as providing services, mining, or staking may be treated as income in some jurisdictions. The timing and amount recognized can depend on local rules.
These categories are not universal. Before calculating what you owe, identify the tax jurisdiction that applies to you and determine how it classifies each type of transaction.
Which Crypto Transactions May Be Taxable?
Not every movement of cryptocurrency automatically creates a tax liability. Transferring assets between wallets you own, for example, is generally different from selling them to another person. However, the treatment depends on the jurisdiction and the nature of the transaction.
| Crypto activity | Potential tax consideration |
| Buying and holding crypto | A purchase alone often does not trigger a disposal gain, but records of acquisition are important. |
| Selling crypto for cash | May create a capital gain or loss. |
| Swapping Bitcoin for Ethereum | May count as disposing of Bitcoin and acquiring Ethereum. |
| Spending crypto on goods or services | May be treated as a disposal of the cryptocurrency used. |
| Receiving staking rewards | May be income when received, when disposed of, or subject to another treatment, depending on local law. |
| Mining cryptocurrency | May create income or business-related tax obligations. |
| Receiving an airdrop | Treatment varies according to the type of distribution and applicable rules. |
| Receiving salary or freelance payment in crypto | May create income-reporting obligations based on the value and timing of receipt. |
| Moving crypto between your own wallets | Often not a disposal, but transaction records can help demonstrate ownership and distinguish transfers from sales. |
This table is a general orientation, not a universal tax classification. A transaction’s label on an exchange does not determine its legal treatment.
How to Calculate Crypto Capital Gains
A common starting point for calculating a capital gain is the difference between the proceeds from a disposal and the asset’s cost basis. Your jurisdiction may require adjustments for fees, currency conversion, asset identification methods, or other factors.
A simplified formula is:
Capital gain or loss = Disposal proceeds − Adjusted cost basis
Consider this example:
You purchase a cryptocurrency for $1,000. Later, you sell it for $1,400. Assume, purely for illustration, that there are no fees or other adjustments and that the applicable rules use those figures.
- Purchase cost: $1,000
- Sale proceeds: $1,400
- Illustrative gain: $400
The $400 is the gain before considering any applicable adjustments or exemptions. It is not necessarily the amount of tax you owe. The tax due, if any, depends on the applicable rules, your circumstances, and the relevant tax rate.
If you sell the asset for $700 instead, the same simplified calculation produces a $300 loss. Whether that loss can offset other gains, be carried forward, or receive any tax recognition depends on local law.
Why Cost Basis Matters
Cost basis records how much you paid to acquire an asset, subject to applicable adjustments. It can become complicated if you purchase the same cryptocurrency at different prices over several months.
For example, imagine buying Bitcoin in three separate transactions at different prices. If you later sell part of your holdings, the amount assigned to the units sold may depend on the cost-basis method permitted or required in your jurisdiction.
Possible methods in some tax systems include first-in, first-out (FIFO), specific identification, or other prescribed approaches. Do not choose a method simply because it produces the lowest apparent tax bill. Use the method permitted by the rules that apply to you and apply it consistently as required.
Are Crypto-to-Crypto Swaps Taxable?
A common misconception is that tax only matters when cryptocurrency is converted into cash.
In some jurisdictions, exchanging one crypto asset for another is treated as a disposal of the asset given up. That means a Bitcoin-to-Ethereum swap may have tax consequences even if you never withdraw money to a bank account.
Imagine acquiring Bitcoin for $2,000 and later exchanging it for another cryptocurrency when the Bitcoin’s relevant disposal value is $2,600. Under a simplified disposal-based system, the transaction could produce a $600 gain before applicable adjustments.
The new asset may also receive its own acquisition value or cost basis under the relevant rules.
This is why crypto tax records should include token swaps, decentralized exchange trades, and other exchanges—not just transactions involving cash.
How Are Staking Rewards and Mining Taxed?
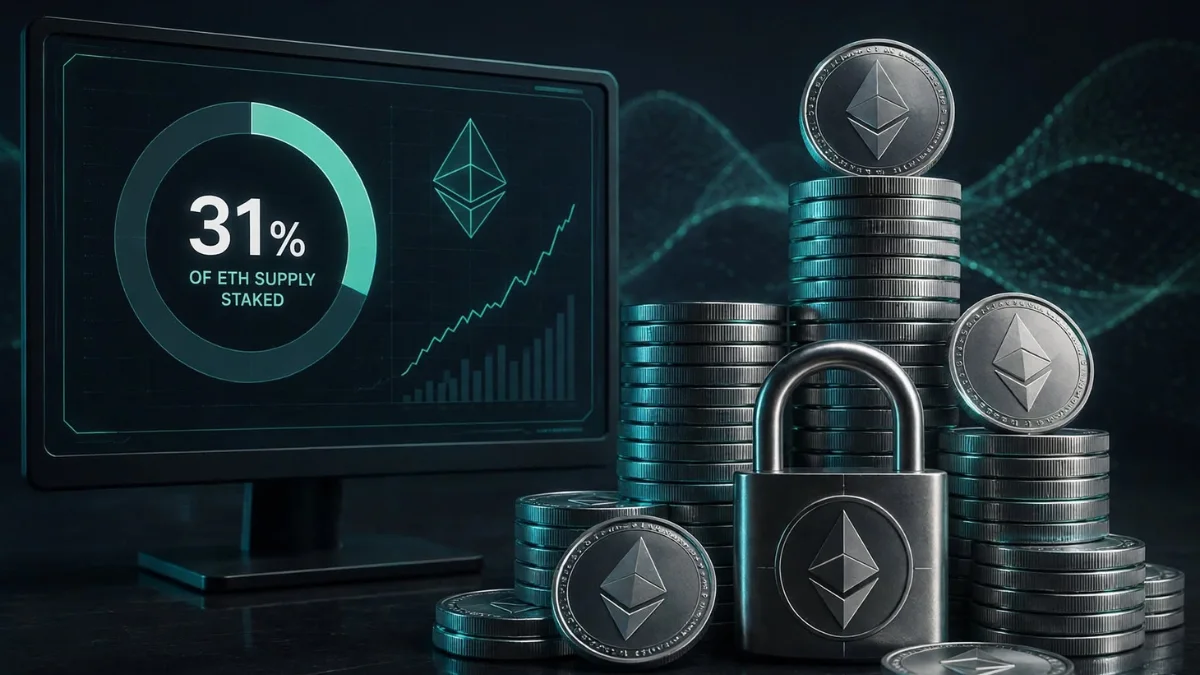
Staking and mining can create tax questions beyond ordinary buying and selling.
Staking Rewards
Staking involves committing or delegating cryptocurrency to help support a proof-of-stake blockchain. In return, a participant may receive additional tokens.
Depending on the jurisdiction, staking rewards may be treated as income when received, when they become accessible, when sold, or under another specific rule. The value used for reporting and the treatment of a later sale may also differ.
Keep records of:
- The date and amount of each reward.
- The cryptocurrency received.
- The value and currency used for valuation.
- The platform or protocol that distributed it.
- Any later sale, exchange, or transfer.
Do not assume that every staking reward is taxed in the same way or at the same time.
Mining Income
Mining uses computing resources to help validate transactions or secure certain blockchain networks. Miners may receive cryptocurrency as a reward.
Tax treatment can depend on whether the activity is occasional, business-like, or conducted through a company. Relevant expenses, equipment, electricity, and the subsequent disposal of mined coins may receive different treatment under local rules.
Someone mining cryptocurrency as a business may have obligations that differ from those of a person who occasionally receives rewards. Keep supporting records and seek professional advice if the activity is substantial.
What About Crypto Airdrops?
Airdrops distribute tokens to eligible wallets, sometimes as part of a project’s launch, community campaign, or user-reward program.
An airdrop does not automatically mean that you owe tax everywhere. However, some jurisdictions may treat certain tokens as income when received or when you gain control of them. Other rules may apply depending on how the distribution occurred.
Maintain records of:
- The project and token received.
- The date you received or gained control of the tokens.
- The quantity and relevant market value, where required.
- Whether the tokens were restricted, inaccessible, or subject to conditions.
- Any later sale or exchange.
Airdrops can be difficult to value when tokens have little liquidity or no reliable market price. Avoid inventing a value just to complete a spreadsheet. Record the available evidence and follow the valuation rules applicable to your jurisdiction.
How to Keep Accurate Crypto Tax Records
Good records are often more useful than trying to find a tax answer after the end of the year. Exchanges can close accounts, transaction histories can become difficult to retrieve, and blockchain activity may be spread across multiple wallets.
Use the CLEAR Crypto Recordkeeping Method to organize your information.
C — Capture every transaction. Record purchases, sales, swaps, fees, rewards, payments, and relevant transfers.
L — Link wallets and accounts. Keep track of which wallets and exchange accounts you control so that transfers between your own accounts are not confused with disposals.
E — Establish acquisition details. Record dates, quantities, purchase values, fees, and other information needed to determine cost basis.
A — Archive supporting evidence. Save exchange statements, wallet transaction IDs, receipts, reward histories, and valuation records.
R — Review and reconcile. Compare your records with exchange statements and on-chain activity. Investigate unexplained deposits, withdrawals, and missing transactions.
A useful transaction log can contain these columns:
| Field | What to record |
| Date and time | When the transaction occurred |
| Transaction type | Purchase, sale, swap, reward, transfer, or payment |
| Asset and quantity | The token and amount involved |
| Value and currency | The relevant value used for records |
| Fees | Trading, network, or other applicable fees |
| Wallet or platform | Where the transaction occurred |
| Transaction ID | A reference that helps verify the activity |
| Cost basis or proceeds | Values needed for the applicable calculation |
| Notes | Context, valuation evidence, or unresolved questions |
Keep records for the period required by your local law. Do not assume that an exchange’s tax report contains every transaction or uses the method required by your tax authority.
Can Crypto Losses Reduce Your Taxes?
A cryptocurrency sold below its relevant cost basis may produce a loss under certain tax systems. However, a recorded loss does not automatically mean that you can deduct it.
Depending on the applicable law, losses may be subject to restrictions, may offset only particular categories of gains, or may not receive the treatment you expect. Some jurisdictions also have rules designed to address transactions that create a loss while the taxpayer retains substantially the same economic exposure. Understanding these rules is important when studying financial strategies and the experiences shared in solopreneur success stories or learning how people build wealth through millionaire success stories.
Before relying on a crypto loss to reduce a tax bill, check:
- Whether the transaction qualifies as a recognized loss.
- Which gains or income, if any, the loss may offset.
- Whether reporting requirements apply even when the overall result is negative.
- Whether special rules apply to related-party trades, repurchases, or other arrangements.
Never assume that a loss is deductible merely because your portfolio declined in value. A market-price decline without a disposal may be treated differently from a realized loss.
Do You Have to Report Crypto if You Did Not Withdraw to a Bank?
Possibly. The need to report cryptocurrency activity does not necessarily depend on whether you withdrew money to a bank account. Selling crypto for another asset, receiving rewards, or spending tokens may create reporting obligations in some jurisdictions. A bank withdrawal is only one possible event in a broader sequence of transactions.
Likewise, moving assets from an exchange to a wallet you control does not necessarily create a taxable disposal, but you should retain evidence showing that the transfer was between your own accounts. Reporting obligations can also apply even when no tax is ultimately payable. If you are unsure how these rules apply to your situation, consulting a tax consultant can help you understand the requirements. Check the rules for your tax residence rather than using bank withdrawals as your only measure of taxable activity.
Crypto Taxes in Pakistan and Other Countries
Crypto tax treatment is jurisdiction-specific. Rules can differ not only between countries but also according to the type of transaction, the taxpayer’s status, and the tax year.
If you live in Pakistan, do not assume that guidance written for the United States, United Kingdom, or another country applies to you. Confirm the current position with a qualified Pakistani tax professional and the relevant official authorities before filing or making a financial decision. This guide does not establish the current Pakistani tax treatment of cryptocurrency.
The same principle applies elsewhere. A country may distinguish between capital gains, business income, employment income, and other categories. It may also impose separate reporting or record-retention requirements.
Before filing, establish:
- Which country or jurisdiction treats you as a tax resident.
- Which tax year and filing deadlines apply.
- How each type of crypto transaction is classified.
- Which valuation and cost-basis rules must be used.
- Whether special reporting forms or disclosures are required.
- How losses, fees, rewards, and cross-border activity should be handled.
If you moved countries during the year, hold assets through foreign platforms, or receive crypto from an overseas employer, the situation may require additional advice.
Should You Use Crypto Tax Software?
Crypto tax software can help organize transactions across exchanges and wallets, calculate gains under supported methods, and produce reports. It is particularly useful when you make frequent trades or use several platforms.
However, software is not a substitute for checking the underlying data or confirming that its tax settings match your jurisdiction.
| Approach | Most useful for | Main limitation |
| Spreadsheet | Small portfolios and straightforward activity | Manual work and a greater risk of data-entry errors |
| Crypto tax software | Many transactions across several platforms | Import errors and jurisdiction-specific settings still need review |
| Tax professional | Complex activity, substantial holdings, business use, or cross-border issues | Cost and the need to provide complete records |
Before relying on a report, verify imported transactions, wallet transfers, missing cost basis, reward valuations, and the selected accounting method. Check that the software supports the relevant country and tax year.
A Practical Crypto Tax Checklist
Before preparing your tax return, work through this checklist:
- Download transaction histories from every exchange you used.
- Collect records from personal wallets and decentralized platforms.
- Identify purchases, sales, swaps, payments, rewards, and airdrops.
- Match transfers between wallets you control.
- Gather transaction fees and acquisition records.
- Review missing or unreliable cost-basis information.
- Confirm the valuation method and transaction classifications required by local law.
- Check whether losses can be recognized and how they may be used.
- Review reporting deadlines and record-retention requirements.
- Consult a qualified tax professional if your circumstances are complex.
Completing these steps throughout the year is usually easier than rebuilding a complete transaction history at filing time.
Frequently Asked Questions About Crypto Taxes
Do I pay tax when I buy Bitcoin?
Buying Bitcoin with ordinary currency and holding it often does not trigger a disposal gain by itself. However, the purchase establishes records that may be needed later. Local reporting rules and special circumstances can differ.
Is swapping Bitcoin for Ethereum a taxable event?
It can be. Some jurisdictions treat the exchange as a disposal of Bitcoin, potentially creating a gain or loss. Check the rules that apply to your tax residence.
Are staking rewards taxable?
They may be. Some tax systems treat staking rewards as income at a particular point, while others use different rules. The treatment of a later sale can be separate from the treatment of receiving the reward.
Do I have to report crypto if I lost money?
Possibly. A loss does not automatically remove reporting obligations, and whether it can reduce other taxable amounts depends on local law.
Are crypto airdrops taxable?
The answer varies. The tax treatment may depend on how the tokens were distributed, when you gained control of them, their value, and the applicable jurisdiction.
Can I calculate crypto taxes using exchange statements alone?
Exchange statements are a useful starting point, but they may not include activity from personal wallets, decentralized exchanges, staking services, or other platforms. Reconcile all relevant activity before relying on a final calculation.
What happens if I cannot find my crypto purchase records?
Try retrieving historical exchange statements, wallet records, transaction IDs, receipts, and other supporting evidence. Do not guess a cost basis without a defensible basis. If important records are missing, consult a qualified tax professional about the method permitted by local rules.
Do crypto tax rules apply to people in Pakistan?
People in Pakistan should verify the current rules and their personal obligations with qualified local tax advice and relevant official sources. Tax treatment can change, and guidance for another country should not be assumed to apply.
Final Thoughts
Crypto taxes are easier to manage when every transaction has a clear record. A purchase, a token swap, a staking reward, and a sale may each raise different questions, even when they all appear in the same crypto wallet.
Start by identifying the rules that apply to your tax residence, maintaining reliable records, and checking how your specific activities are classified. If you trade frequently, earn crypto through several channels, or have cross-border holdings, professional guidance can help you avoid relying on assumptions.
Disclaimer: This article is for general educational purposes only and is not tax, legal, accounting, or investment advice. Cryptocurrency tax treatment varies by jurisdiction and may change. Consult a qualified professional about your circumstances before filing a tax return or making a tax-related decision.