Building wealth can feel impossible when you are starting with little money. Rent, food, bills, and unexpected expenses can consume most of your income before you have anything left to save.
But wealth does not begin with a large investment account or a business that suddenly takes off. It begins with creating a gap between what you earn and what you spend, then using that gap to build financial security and acquire assets over time.
The process is not equally easy for everyone. Your income, responsibilities, location, and access to opportunities all matter. Still, you can make progress by following a practical plan: increase your earning power, control unnecessary expenses, protect yourself from financial shocks, and put money toward long-term goals.
Key Takeaways
- Building wealth from nothing starts with improving your financial position, not chasing a quick return.
- Increasing income can create more room to save when essential expenses already consume most of your paycheck.
- An emergency fund helps prevent unexpected bills from turning into expensive debt.
- Investing can support long-term growth, but it involves risk and works best with a suitable time horizon.
- Consistent financial decisions matter more than trying to become rich overnight.
What Does Building Wealth From Nothing Actually Mean?
Building wealth from nothing means improving your net worth when you have limited savings, few assets, or significant financial obligations.
Your net worth is the value of what you own minus what you owe.
For example, imagine you have $1,000 in savings, $500 in other assets, and $2,000 in debt. Your net worth is negative $500.
As you pay down debt, save money, and acquire assets, that number can improve even if the progress feels slow at first.
The objective is not simply to earn more money. It is to keep more of what you earn and gradually turn it into financial resources that support your future.
1. Understand Where Your Money Goes
Before trying to build wealth, establish a clear picture of your current financial situation.
Review the last 30 days of spending. Separate your expenses into three groups:
- Essentials: Housing, groceries, utilities, transportation, and necessary healthcare.
- Financial commitments: Debt payments, insurance, and other obligations.
- Flexible spending: Entertainment, subscriptions, convenience purchases, and nonessential shopping.
You do not need to eliminate every enjoyable expense. The goal is to identify spending that does not provide enough value for its cost.
Suppose you discover that several unused subscriptions and frequent convenience purchases cost $80 a month. Redirecting that money toward debt repayment or savings gives it a more useful purpose.
If your essential expenses already exceed your income, cutting small purchases will not solve the underlying problem. You may need to focus more heavily on increasing income, reducing major costs, or accessing available assistance.
2. Increase Your Income Before Chasing Investments
When you have very little money, your ability to earn can be more important than the return on your savings.
Consider two scenarios.
Someone with $500 who earns a hypothetical 5% annual return would gain $25 over a year before fees and taxes. Someone who increases their monthly income by $200 has the potential to create $2,400 in additional annual income before expenses and taxes.
These are illustrations, not guaranteed outcomes, but they show why earning power matters when your starting capital is small.
Look for opportunities that match your existing skills and resources.
Ways to increase your earning power
- Learn a skill that employers or clients are willing to pay for.
- Negotiate a raise when your responsibilities and results support one.
- Apply for better-paying roles in your field.
- Offer freelance services using skills you already possess.
- Sell a useful digital product or specialized resource.
- Explore a small business after testing whether customers will pay for it.
For unconventional earning opportunities, explore ways to make money and identify options that fit your circumstances.
Avoid spending heavily on courses, equipment, or business tools before you have evidence that the opportunity is worth pursuing.
3. Create a Small Financial Cushion
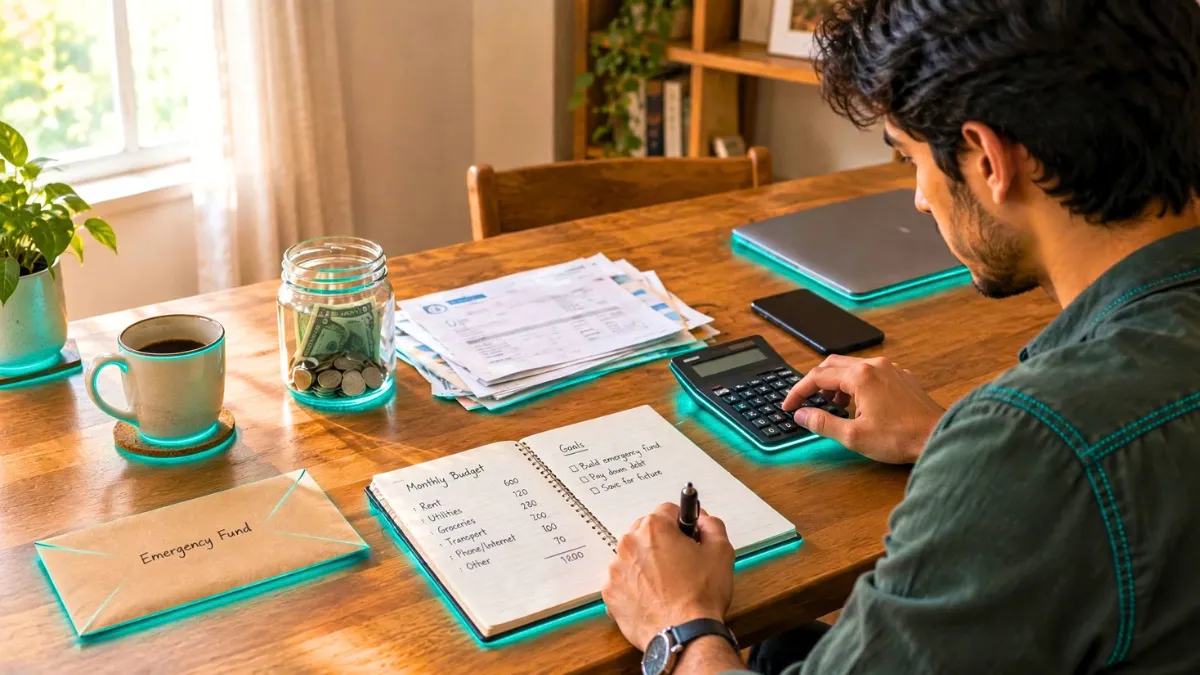
Unexpected expenses can interrupt wealth building. A car repair, medical bill, or temporary loss of income can force you to borrow money or sell investments at an inconvenient time.
An emergency fund provides a buffer against these events.
If saving several months of expenses feels impossible, start with a smaller target that you can realistically reach. Your first milestone might cover one common unexpected bill. You can expand it as your finances improve.
Keep emergency savings somewhere safe and accessible. Money needed for emergencies generally should not depend on stock market performance.
The appropriate amount depends on your income stability, household responsibilities, essential expenses, and access to other financial support.
4. Deal With Expensive Debt
High-interest debt can make it harder to build wealth because part of your income goes toward interest instead of savings and investment.
List your debts with their balances, interest rates, and minimum payments. Continue making required payments while choosing a repayment strategy.
Two common approaches are:
Debt avalanche: Direct extra payments toward the debt with the highest interest rate first. This can reduce total interest costs, assuming other terms remain comparable.
Debt snowball: Direct extra payments toward the smallest balance first. Paying off an account can provide a sense of progress and help you maintain momentum.
Neither method eliminates the need to make minimum payments on other debts.
You may also need a small emergency buffer while repaying debt so that every unexpected expense does not lead to additional borrowing.
The right balance between saving and debt repayment depends on interest rates, penalties, and your immediate financial needs.
5. Learn to Save Without Depending on Motivation
Saving becomes easier when it is part of your routine rather than a decision you make at the end of each month.
If your income allows it, arrange an automatic transfer into savings shortly after payday. Start with an amount that will not cause you to miss essential payments.
As your income grows, consider increasing the transfer.
For example, saving $50 every month adds up to $600 over 12 months, before any interest. The amount may seem modest, but the habit creates a foundation for larger contributions later.
If your budget cannot support that amount, start smaller. A sustainable contribution is more useful than an ambitious target that forces you back into debt.
For practical ways to free up money without making everyday life miserable, see ways to save money without feeling miserable.
6. Start Investing When Your Finances Can Support It
Investing can help build wealth over long periods, but it is not a substitute for having enough money to cover essential expenses.
Before investing, consider whether you have addressed urgent financial needs, established some emergency savings, and made a plan for expensive debt.
Then learn about investment options that suit your goals, time horizon, and tolerance for losses.
Common categories include:
- Diversified stock funds: Provide exposure to multiple companies, but their values can fall substantially.
- Bond funds or individual bonds: May provide interest income, but carry risks such as credit risk and changing interest rates.
- Interest-bearing savings products: Can preserve access to cash, depending on the product and applicable protections, but may not grow faster than inflation.
- Retirement accounts: May offer tax advantages depending on the country and account rules.
- Business ownership: Can build value and income, but also carries the risk of losing invested money.
You do not need to master every investment category at once. Start by understanding fees, diversification, taxes, and the possibility of losing money.
Avoid borrowing to invest or placing money needed for near-term expenses into volatile assets.
7. Build Assets That Can Grow Over Time
An asset is something you own that has economic value. Some assets can generate income, appreciate in value, or support your ability to earn.
Examples include investments, a profitable business, intellectual property, and certain digital products.
A useful digital product might be a spreadsheet, a specialized template, or a practical guide. It can potentially be sold repeatedly, although creating the product is only part of the work. You still need demand, distribution, customer support, and maintenance where appropriate.
A business can also become an asset if it develops reliable processes, customer relationships, and value beyond the owner’s immediate labor.
The important distinction is between owning something valuable and simply spending money on something that might become valuable. A product or business idea is not a profitable asset until there is evidence that it can deliver value.
8. Avoid Lifestyle Inflation
As your income increases, it is tempting to upgrade everything immediately: your car, home, wardrobe, and daily spending.
There is nothing inherently wrong with enjoying the money you earn. The problem arises when every increase in income is matched by an increase in expenses.
Suppose your monthly income rises by $400. You could use the entire amount to increase spending, or direct part of it toward savings, debt repayment, and investments while keeping some for enjoyment.
That approach allows your lifestyle to improve without sacrificing all the progress your higher income could create.
A simple rule is to decide how you will allocate an income increase before the extra money reaches your account.
9. Build More Than One Source of Income Carefully
A second income source can improve financial flexibility, especially when your main income is limited or vulnerable to disruption.
However, more income streams are not automatically better. Managing several small projects can consume time without producing meaningful profit.
Start with one additional opportunity and measure the results. If it becomes profitable and manageable, decide whether to expand it or build something related.
For example, a freelance designer might first offer services, then develop reusable templates based on recurring client needs. The second product builds on experience gained from the first activity.
The objective is to create income that supports your financial plan without exhausting your time and energy.
10. Give Your Wealth-Building Plan a Long-Term Direction
Wealth building becomes easier to manage when you know what you are working toward.
Your priorities may include paying off debt, building emergency savings, purchasing a home, funding education, or preparing for retirement.
Write down a goal, a target amount, and a realistic timeline. Then break the goal into smaller actions.
For example, a $1,200 savings target can be approached through monthly contributions of $100 over 12 months, before interest and assuming you do not withdraw from the account.
Review your progress periodically. If your income changes or an unexpected expense occurs, adjust the plan rather than treating one difficult month as failure.
A Practical 90-Day Wealth-Building Plan
You do not need to change every part of your financial life at once. Use the first three months to establish a foundation.
| Period | Main focus | Actions |
| Days 1–30 | Understand your finances | Review spending, list debts, calculate net worth, and choose one priority |
| Days 31–60 | Create stability | Start a manageable savings habit, address expensive debt, and explore one income improvement |
| Days 61–90 | Build momentum | Review progress, refine your budget, and create a realistic savings or investment plan |
Your results will depend on your starting point. If you have very little disposable income, your first 90 days may be about stabilizing cash flow rather than investing. That is still meaningful progress.
Common Mistakes That Slow Wealth Building
Chasing quick riches. Promises of guaranteed profits, unusually high returns, or effortless income deserve skepticism. Understand how an opportunity works before risking money.
Ignoring small financial leaks. Repeated fees, unused subscriptions, and expensive borrowing can gradually reduce the money available for your goals.
Investing before understanding the risk. An investment that looks attractive may be unsuitable if you need the money soon or cannot tolerate a loss.
Comparing your starting point with someone else’s results. Other people’s visible wealth does not reveal their debts, family support, income, or financial risks.
Giving up when progress is slow. Financial progress is rarely a straight line. A job loss, illness, family expense, or economic downturn can change your plans. Adjusting your strategy is more useful than assuming you have failed.
Frequently Asked Questions
Can you build wealth with a low income?
Yes, but it may take longer, and the available choices depend on essential expenses and other obligations. Increasing income, accessing eligible support, managing debt, and building even small savings can help improve your financial position over time.
How long does it take to build wealth from nothing?
There is no fixed timeline. It depends on your income, spending, debt, investment returns, family responsibilities, and unexpected events. Focus on measurable progress instead of expecting a particular net worth by a certain age.
Should you save money or invest first?
Many people benefit from building accessible emergency savings and addressing expensive debt before investing substantial amounts. The right order depends on your circumstances, the cost of your debt, and the urgency of your financial obligations.
Can you build wealth without starting a business?
Absolutely. A business is only one possible route. Career growth, disciplined saving, suitable investments, debt management, and retirement planning can all contribute to wealth building.
What is the biggest mistake beginners make?
One common mistake is searching for a shortcut instead of building a repeatable financial system. A plan that combines realistic spending, growing earning power, savings, and appropriate long-term investing is generally more sustainable than relying on a speculative opportunity.
The Bottom Line
Building wealth from nothing is not about finding one secret investment or launching a business that becomes successful overnight. It is about improving your financial position step by step.
Start by understanding your money, strengthening your earning power, creating a safety cushion, and addressing expensive debt. Then consider assets and investments that match your goals and risk tolerance.
Your next action: Calculate your current monthly income, essential expenses, and debt payments. Identify one change you can make this month, whether that means increasing earnings, reducing a major expense, or starting a small savings habit.
The first milestone is not becoming rich. It is creating enough financial breathing room to make your next decision from a stronger position.
Disclaimer:
This article is for informational and educational purposes only. It does not constitute personalized financial, tax, or investment advice. Investment values can fall, and past performance does not guarantee future results.
Add a clear starting-budget example Add a low-income starting path